Call CA Tally HelpDesk
+91 9205471661,
7428779101
Introduction: Why Cash Flow and Credit Management Have Become Critical for Businesses in 2026
In 2026, retailers, wholesalers and distributors across India are facing growing pressure to maintain healthy cash flow while managing customer credit, supplier payments, inventory purchases and daily operating expenses. A business may record strong sales and still struggle to pay suppliers because customers delay their payments. Rising operating costs, competitive credit terms and unpredictable collection cycles make financial planning increasingly important. For businesses dependent on credit sales, one overdue payment can affect inventory replenishment, employee salaries and future orders.
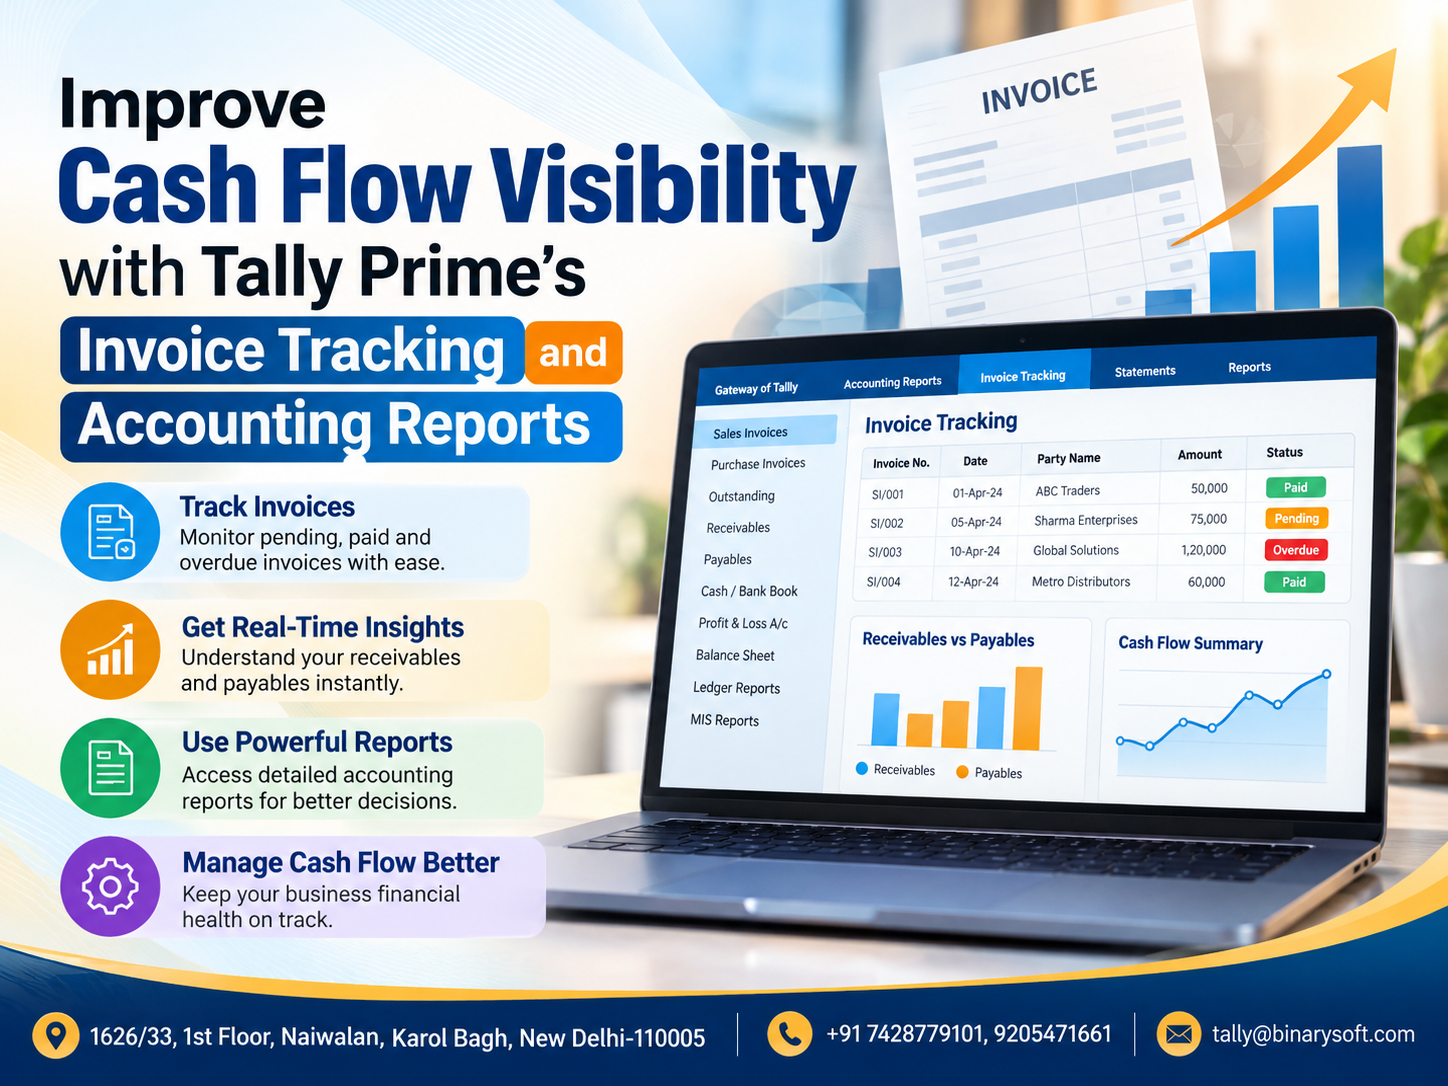
Tally Prime helps businesses organize receivables, payables, credit limits, banking transactions and financial reports within an integrated accounting environment. Its bill-wise tracking, outstanding analysis and cash flow reporting features provide useful information for monitoring financial commitments. By combining accurate accounting records with disciplined collection and payment processes, retailers, wholesalers and distributors can improve liquidity visibility, reduce avoidable credit risks and make more confident business decisions.
1. Understanding Cash Flow and Credit Management
Cash flow management involves monitoring money entering and leaving a business.
Cash inflows generally include customer collections, cash sales, loans and other receipts. Cash outflows include supplier payments, salaries, rent, taxes, transportation and other expenses.
Credit management focuses on controlling the amount customers owe, determining suitable payment terms and ensuring timely collection.
These activities are closely connected.
A wholesale distributor may sell goods worth ₹20 lakh in one month, but if customers pay after 60 days, the business may face difficulty meeting immediate expenses.
Strong sales figures do not automatically mean sufficient cash availability.
Why effective management matters
-
Maintains sufficient funds for daily operations.
-
Reduces overdue customer payments.
-
Supports timely supplier settlements.
-
Helps avoid unnecessary short-term borrowing.
-
Improves inventory purchasing decisions.
-
Identifies customers with excessive outstanding balances.
-
Supports business expansion through better financial planning.
Tally Prime provides accounting and reporting features that help businesses monitor these activities using recorded financial information.
2. How Tally Prime Supports Cash Flow Management
Tally Prime integrates sales, purchases, receipts, payments and financial reporting.
When transactions are recorded correctly, management can review their impact on customer balances, supplier obligations and cash or bank accounts.
For example, a retailer receiving ₹50,000 from a customer can record the receipt against the relevant invoice.
The customer outstanding balance is then updated according to the transaction allocation.
Similarly, payments made to suppliers can be recorded against outstanding purchase bills.
This coordinated approach reduces the need to maintain separate payment registers and accounting spreadsheets.
Tally Prime also provides reports that help businesses review cash and bank balances, outstanding bills and financial performance.
However, cash flow reporting reflects recorded transactions. It should not be confused with a guaranteed prediction of future cash availability.
Businesses should combine accounting reports with expected collections, payment schedules and realistic financial forecasts.
3. Customer Credit Limit Management in Tally Prime
Extending credit helps retailers and distributors maintain relationships with regular customers. However, uncontrolled credit sales can create serious financial difficulties.
Tally Prime allows businesses to define credit limits and credit periods for customer ledgers. These settings help employees monitor outstanding exposure and identify transactions requiring review.
For example, a wholesale distributor may assign a ₹2 lakh credit limit and a 30-day credit period to a regular customer.
If the customer already owes ₹1.80 lakh, a proposed additional credit sale of ₹50,000 would increase the outstanding amount to ₹2.30 lakh.
The business can use its configured credit checks and internal approval process to evaluate this exposure.
Credit controls should be reviewed periodically according to customer payment history, business relationships and financial capacity.
4. Bill-Wise Receivables and Payment Tracking
Bill-wise tracking is one of the most useful features for businesses that regularly sell goods on credit.
Instead of viewing only a customer's total outstanding balance, businesses can monitor individual invoices, due dates and pending amounts.
Illustrative receivables report
|
Customer
|
Invoice amount
|
Received
|
Pending
|
|---|
|
Retailer A
|
₹1,50,000
|
₹1,00,000
|
₹50,000
|
|
Dealer B
|
₹2,00,000
|
₹75,000
|
₹1,25,000
|
|
Distributor C
|
₹90,000
|
₹40,000
|
₹50,000
|
|
Total
|
₹4,40,000
|
₹2,15,000
|
₹2,25,000
|
When a receipt is allocated against the correct bill reference, the corresponding pending balance is updated.
This helps the accounts department identify unpaid invoices and prepare accurate customer statements.
Bill-wise records also make it easier to investigate payment disputes.
5. Ageing Analysis for Overdue Customer Payments
Not every outstanding invoice carries the same collection risk.
A payment delayed by five days may require a routine reminder, while an invoice overdue by ninety days may require management attention.
Tally Prime supports ageing analysis based on invoice dates or due dates, allowing businesses to classify outstanding amounts into different periods.
Example of ageing analysis
|
Ageing period
|
Outstanding amount
|
Suggested action
|
|---|
|
0–30 days
|
₹3,50,000
|
Regular monitoring
|
|
31–60 days
|
₹1,75,000
|
Customer follow-up
|
|
61–90 days
|
₹90,000
|
Priority collection review
|
|
Above 90 days
|
₹60,000
|
Management escalation
|
|
Total
|
₹6,75,000
|
|
Ageing analysis helps businesses identify customers whose payment behaviour requires attention.
It can also support decisions about revised credit limits, advance payments and future credit sales.
However, ageing reports do not automatically establish whether an amount is recoverable. Businesses should evaluate disputes, payment commitments and applicable accounting requirements before classifying receivables as doubtful.
6. Supplier Payment and Payables Management
Cash flow management is not limited to collecting customer payments. Businesses must also manage supplier obligations carefully.
Tally Prime allows businesses to record purchase invoices and track outstanding supplier balances.
For example, a distributor may purchase inventory worth ₹5 lakh on 45-day credit terms.
The accounts department can record the purchase and monitor the amount due.
When payment is made, the relevant voucher can be allocated against the supplier bill.
Supplier outstanding reports help management plan payment schedules and identify approaching due dates.
Timely supplier payments can strengthen commercial relationships and improve the reliability of future supplies.
At the same time, businesses should avoid paying obligations earlier than necessary when doing so would create unnecessary cash pressure, unless early-payment discounts or contractual requirements justify it.
7. Cash Flow Statements and Financial Reporting
Tally Prime provides financial reports that help businesses understand their financial position and cash movements.
These include Cash Flow, Funds Flow, Profit & Loss Account, Balance Sheet, receivables and payables reports.
Illustrative monthly cash movement
|
Particulars
|
Amount
|
|---|
|
Opening cash and bank balance
|
₹4,00,000
|
|
Customer collections
|
₹8,50,000
|
|
Other receipts
|
₹50,000
|
|
Supplier payments
|
₹6,00,000
|
|
Salaries and operating expenses
|
₹2,00,000
|
|
Tax and other payments
|
₹75,000
|
|
Closing cash and bank balance
|
₹4,25,000
|
This example illustrates how business liquidity can be evaluated through receipts and payments.
Management should review cash movement alongside receivables and upcoming payment commitments.
A profitable business may still face liquidity pressure if substantial sales remain unpaid.
8. Cash Flow Forecasting for Better Financial Planning
Cash flow forecasting helps businesses estimate future receipts and payments.
A practical forecast may consider customer collection commitments, supplier due dates, payroll, rent, taxes and planned inventory purchases.
For example, a distributor expecting ₹10 lakh in collections next month may also have ₹8 lakh in scheduled payments.
The apparent surplus is ₹2 lakh, but management must consider uncertainty in collections and unexpected expenses.
Businesses can use Tally Prime reports as inputs for a separate weekly or monthly cash forecast.
A useful forecast should include conservative assumptions rather than treating every outstanding invoice as guaranteed cash.
This approach helps management anticipate potential funding gaps and adjust purchasing or collection priorities.
9. Inventory Management and Working Capital
Inventory has a direct effect on cash flow.
Excess stock ties up money that could otherwise be used for supplier payments, salaries or expansion.
Insufficient stock can result in lost sales and customer dissatisfaction.
Tally Prime's inventory reports help businesses review stock quantities, movement and valuation.
For example, a retailer may discover that ₹4 lakh is invested in products with limited demand.
Management can evaluate whether promotional offers, revised purchasing quantities or supplier negotiations would improve inventory turnover.
Combining inventory analysis with receivables and payables information provides a broader understanding of working-capital requirements.
10. Banking and Reconciliation for Cash Accuracy
Accurate bank records are essential for dependable cash-flow reporting.
Businesses should regularly compare recorded receipts and payments with actual bank transactions.
Tally Prime provides bank reconciliation functionality and supported banking utilities that can assist this process.
A customer may claim to have paid ₹75,000, but the amount might remain unmatched in the accounting records.
Regular reconciliation helps identify such differences before they create larger reporting problems.
It can also reveal duplicate entries, omitted bank charges and incorrectly recorded transactions.
11. A Story of Financial Pressure: When Strong Sales Were Not Enough
The following story is fictional and illustrates a common business challenge.
For fifteen years, Sandeep operated a wholesale distribution business in Delhi.
His father had started the company with limited savings, and Sandeep had worked hard to expand its customer network.
The business was growing. Sales increased, new retailers placed orders and the warehouse remained busy.
Yet something was wrong.
Despite healthy sales, Sandeep frequently struggled to arrange money for supplier payments.
One morning, an important supplier informed him that fresh deliveries would be delayed until older invoices were cleared.
At the same time, several customers requested additional goods on credit.
Sandeep opened his accounting registers and realized that large amounts were outstanding from customers.
Some invoices had remained unpaid for more than ninety days.
He felt overwhelmed.
The business appeared successful from the outside, but he was worried about paying employees and maintaining sufficient stock.
That evening, he remembered how his father had carefully recorded every customer payment in a handwritten ledger.
Sandeep realized that business growth had made the old process inadequate.
He decided to improve credit monitoring using Tally Prime.
Customer ledgers were reviewed, bill-wise tracking was introduced and credit limits were established.
Employees began checking ageing reports and following up on overdue invoices systematically.
Over time, the business developed a more disciplined collection process.
Sandeep also started reviewing supplier commitments and expected receipts before approving major purchases.
For him, financial control was not simply about improving reports.
It was about protecting employees, customers and the business his family had spent years building.
12. Case Study One: Electrical Goods Wholesaler in Delhi
Illustrative case study; figures and outcomes are hypothetical.
Business background
An electrical goods wholesaler supplied retailers and contractors across Delhi NCR.
The company generated substantial credit sales but maintained customer outstanding information through separate spreadsheets.
Challenges
-
Delayed customer collections.
-
Difficulty identifying overdue invoices.
-
Limited visibility into customer credit exposure.
-
Irregular collection follow-ups.
-
Pressure on supplier payments.
Proposed Tally Prime implementation
The company configured bill-wise receivables, customer credit periods and credit limits.
Employees began recording receipts against individual invoices.
Management introduced weekly reviews of outstanding and ageing reports.
Illustrative improvement targets
|
Performance indicator
|
Before
|
Target
|
|---|
|
Average collection period
|
65 days
|
45 days
|
|
Overdue invoice review
|
Monthly
|
Weekly
|
|
Customer credit monitoring
|
Manual
|
Configured ledger controls
|
|
Payment follow-ups
|
Reactive
|
Scheduled
|
|
Receivables reporting
|
Spreadsheet compilation
|
Accounting reports
|
Expected business impact
The proposed system would help management identify delayed collections earlier and make better-informed credit decisions.
Reducing the average collection period could release working capital for inventory purchases and daily expenses.
Actual improvements would depend on customer behaviour, collection procedures and consistent implementation.
13. Case Study Two: FMCG Distributor Managing Supplier Payments
Illustrative case study; figures are hypothetical.
Business background
An FMCG distributor supplied packaged consumer products to supermarkets and retail stores.
The business purchased inventory from multiple suppliers and offered credit facilities to regular customers.
Challenges
The distributor frequently experienced mismatches between expected collections and scheduled supplier payments.
Management also lacked a structured process for evaluating upcoming financial commitments.
Proposed solution
The business introduced bill-wise receivable and payable tracking through Tally Prime.
Customer credit terms were reviewed, and supplier payment schedules were organized.
Management began using cash flow reports and outstanding statements to prepare weekly cash forecasts.
Expected improvements
The proposed approach would provide better visibility into upcoming payments and overdue customer balances.
It would also help management plan inventory purchases according to expected cash availability.
Key lesson
Cash flow improves when businesses coordinate sales collections, purchasing decisions and supplier payments rather than managing each activity separately.
14. Step-by-Step Guide to Credit Management in Tally Prime
Businesses can establish a structured credit management workflow through the following process.
Step 1: Review customer and supplier ledgers. Ensure party records are accurate and duplicate ledgers are identified.
Step 2: Enable bill-wise tracking. Open Gateway of Tally, select F11 Features and enable the relevant bill-wise accounting option.
Step 3: Configure customer credit terms. Enter suitable credit periods and limits in customer ledgers, enabling the required configuration options.
Step 4: Record credit sales. Create sales invoices with appropriate bill references and due dates.
Step 5: Allocate customer receipts. Record receipt vouchers against the correct outstanding invoices.
Step 6: Review receivables. Use Alt+G (Go To) to locate Bills Receivable or relevant outstanding reports.
Step 7: Examine ageing. Review balances according to invoice date or due date.
Step 8: Monitor supplier payables. Check upcoming payment commitments and overdue purchase bills.
Step 9: Reconcile bank accounts. Verify that recorded collections and payments match bank transactions.
Step 10: Review cash flow. Evaluate cash movements and prepare a separate forward-looking cash forecast.
The availability and labels of configuration options may vary by software release.
15. Tally Prime on Cloud for Remote Financial Monitoring
Business owners frequently need access to financial information while travelling or managing multiple branches.
A suitably configured cloud-hosted Tally Prime environment can allow authorized users to access accounting records from approved locations.
For example, a distributor visiting suppliers may review customer receivables and bank balances before approving a large purchase.
The accounts team can continue recording daily transactions in the centralized environment.
Cloud hosting can reduce dependence on one office computer, but it requires suitable licensing, connectivity, security controls and backup arrangements.
Businesses should evaluate these requirements before selecting a cloud solution.
16. Best Practices for Stronger Credit Control
Effective credit management requires regular review and clear internal responsibilities.
Businesses should establish customer credit policies, maintain accurate invoice references and monitor overdue amounts.
Credit limits should be reviewed when customers demonstrate changing payment behaviour.
Collection employees should document payment commitments and escalate unresolved disputes.
Supplier payment schedules should be compared with realistic expected collections.
Management should also maintain a cash reserve where feasible and avoid making large purchasing commitments solely on the basis of uncollected sales.
Combining these practices with Tally Prime's accounting reports can support more dependable financial decisions.
17. How Binarysoft Technologies Can Help
Binarysoft Technologies, an Authorized Tally Partner based in Karol Bagh, New Delhi, can assist businesses in evaluating Tally Prime accounting and financial management requirements.
Retailers, wholesalers and distributors can discuss customer credit controls, bill-wise outstanding tracking, supplier payment management, cash flow reporting and related accounting workflows.
Businesses seeking remote access can also explore suitable cloud-hosting arrangements according to their operational requirements.
The objective is to build a reliable accounting process that supports better collection planning, financial visibility and business continuity.
Conclusion
Advanced cash flow and credit management are essential for retailers, wholesalers and distributors that depend on customer collections and regular supplier payments.
Tally Prime provides useful tools for monitoring receivables, payables, credit limits, outstanding invoices and financial reports.
Bill-wise tracking and ageing analysis can help businesses identify overdue payments and improve collection planning.
Cash flow reports, bank reconciliation and inventory analysis provide additional information for managing working capital.
However, successful financial management depends on more than software. Businesses must establish clear credit policies, maintain accurate accounting records and review financial commitments regularly.
With appropriate implementation and disciplined financial practices, Tally Prime can help businesses improve liquidity visibility, reduce avoidable credit exposure and make more confident decisions.
Powered by Binarysoft Technologies
Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact us: +91 7428779101, 9205471661
Email us: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Monday to Friday
Website: www.tallyatcloud.com
Frequently Asked Questions
What is cash flow management in Tally Prime?
Cash flow management involves reviewing recorded receipts, payments and financial reports to understand money entering and leaving a business.
Can Tally Prime track customer outstanding payments?
Yes. Businesses can monitor customer balances, individual unpaid invoices, due dates and overdue amounts.
Does Tally Prime support customer credit limits?
Yes. Businesses can configure credit limits and credit periods in relevant customer ledgers.
What is bill-wise tracking in Tally Prime?
Bill-wise tracking allows businesses to maintain outstanding amounts against individual invoices and allocate receipts or payments to the appropriate references.
CA. Kairav Dalmia focuses on GST reporting, bookkeeping controls, and accounting automation for trading and service businesses. He translates technical accounting requirements into practical processes that businesses can follow in their daily operations.