Call CA Tally HelpDesk
+91 9205471661,
7428779101
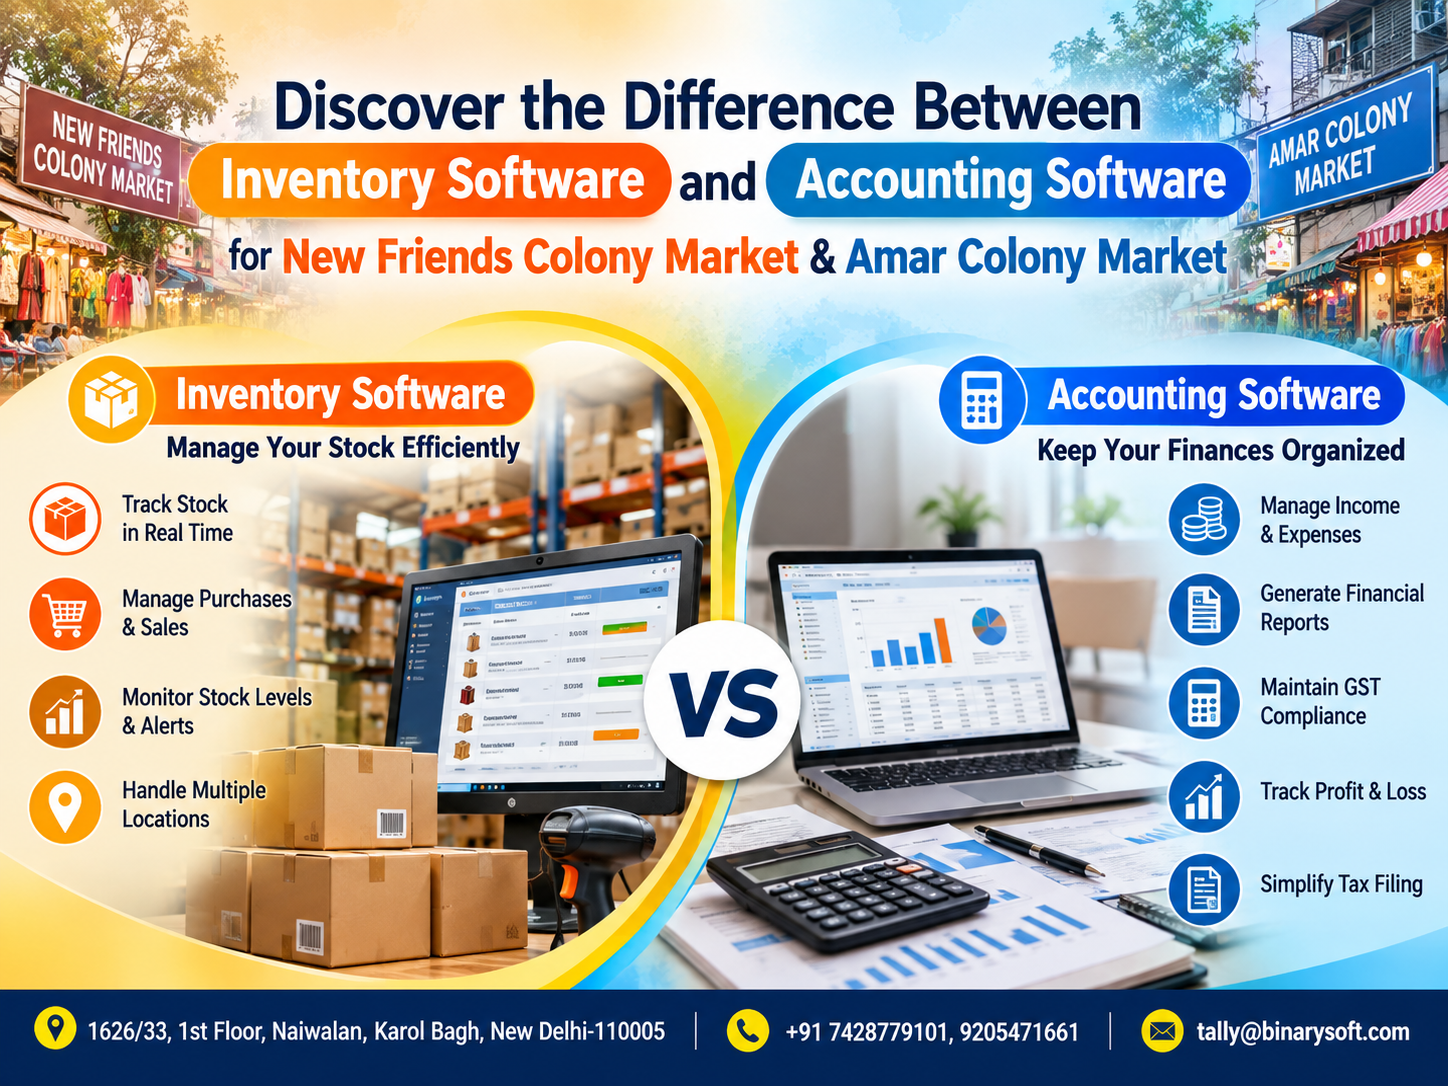
What Changed in 2026? Why Businesses Need Better Control Over Stock and Accounts
In 2026, businesses in New Friends Colony Market and Amar Colony Market are dealing with a challenge that goes far beyond simply recording sales. Customers expect faster billing, businesses manage more product varieties, GST compliance requires accurate records, and owners want to know their stock and financial position without waiting until month-end. This pressure has exposed an important technology gap: many businesses still confuse inventory software with accounting software. Inventory software primarily helps control products, quantities, purchases, sales and stock movement, while accounting software focuses on money, ledgers, receivables, payables, expenses, taxation and financial reporting. Choosing the wrong system can create duplicate work and incomplete visibility. Choosing a solution that connects inventory with accounting can provide something far more valuable: one reliable view of stock, sales, outstanding payments, GST obligations, profitability and overall business performance.
Inventory Software vs Accounting Software: Why the Difference Matters
For a small business, inventory and accounting may initially appear to be the same thing.
A shop owner purchases goods, stores them, sells them and collects payment. Since every stock transaction ultimately has a financial impact, it is easy to assume that any software capable of recording sales can manage the entire business.
But as a business expands, the difference becomes significant.
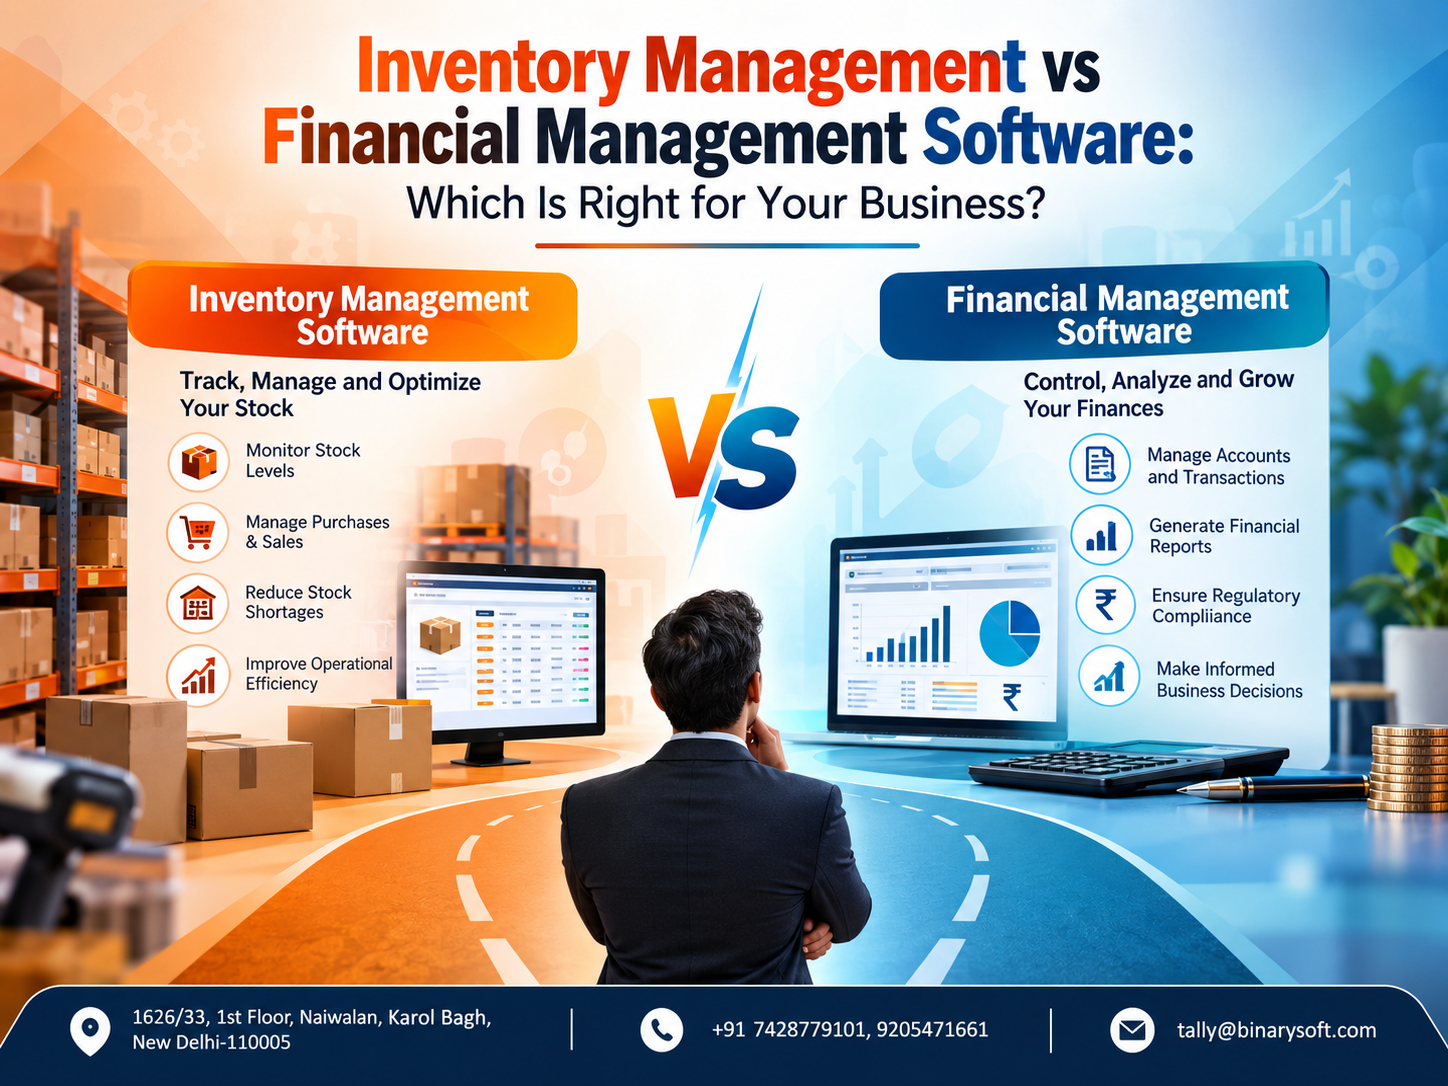
Inventory software answers questions such as:
What products are currently available?
Which items are running low?
How many units were purchased?
How many units have been sold?
Which products are moving quickly?
Where is a particular stock item located?
Accounting software answers a different set of questions:
How much money did the business earn?
How much does the business owe suppliers?
How much do customers still have to pay?
What are the business expenses?
What is the profit or loss?
What is the GST impact of transactions?
What do the financial statements show?
For businesses operating in New Friends Colony Market and Amar Colony Market, understanding this difference can help determine whether they need a specialised stock-management application, accounting software, or an integrated business-management solution.
What Is Inventory Management Software?
Inventory management software is designed primarily to track physical goods.
Suppose a retailer starts the morning with 100 units of a product. During the day, 25 units are sold and another 40 units arrive from a supplier.
A proper inventory system should make it easy to determine the updated quantity without manually counting every item.
But modern inventory management goes considerably beyond simple quantity tracking.
Depending on the software and configuration, businesses may manage stock groups, categories, units of measurement, godowns or locations, batch information, purchase orders, sales orders, reorder levels and stock valuation.
For retailers, wholesalers, distributors and product-based businesses, this information can be critical.
A business can be profitable on paper and still face operational problems if popular items repeatedly go out of stock or money remains blocked in slow-moving inventory.
What Is Accounting Software?
Accounting software focuses on the financial side of business transactions.
Every business needs to know not only what it has sold but also what happened financially because of that sale.
If merchandise worth ₹50,000 is sold on credit, inventory may decrease immediately, but cash has not yet been received.
An accounting system records the amount receivable from the customer.
Similarly, if goods are purchased from a supplier on credit, stock may increase while a payable is created.
Accounting software therefore helps businesses manage areas such as sales, purchases, receipts, payments, journals, customer balances, supplier balances, expenses, taxation and financial reports.
Depending on the software, businesses can also generate reports such as the Profit & Loss Account, Balance Sheet, cash-flow information, outstanding receivables and payables, and other management reports.
Inventory Software vs Accounting Software: The Main Difference
The simplest way to understand the difference is:
Inventory software tells you what is happening to your goods.
Accounting software tells you what is happening to your money and financial records.
Consider a garment retailer in Amar Colony Market.
If 20 shirts are purchased, an inventory system records the additional stock. If five shirts are sold, it reduces the available quantity.
Accounting software looks at the same transactions financially. It records the purchase value, supplier liability, sales revenue, customer payment, taxes and related accounting impact.
The transaction is the same, but the information required by the business owner is different.
This is why growing businesses increasingly look for systems where stock and accounting work together.
A New Friends Colony Business Owner Who Discovered the Gap Too Late
Consider the story of a fictional business owner, Rajiv, running a growing home-accessories store near New Friends Colony Market.
For years, Rajiv relied on a billing application for sales and a spreadsheet for inventory. His accountant maintained the financial records separately.
When the business was small, the arrangement appeared manageable.
Then sales started growing.
More suppliers were added. New product categories arrived every month. Customers began placing orders through phone calls and messaging apps as well as visiting the store.
Rajiv was happy with the growth until one Saturday evening when a regular customer requested 12 pieces of a premium product for an urgent order.
His spreadsheet showed 17 units available.
The staff searched the shelves.
Only four could be found.
The remaining quantity had already been sold or adjusted, but the spreadsheet had not been updated correctly.
The customer went elsewhere.
What bothered Rajiv was not merely the lost sale. He realised that he had been making purchasing decisions using information he could not completely trust.
During the following week, he compared invoices, purchase records, physical inventory and accounting entries.
There were several small differences.
None looked disastrous individually. Together, however, they showed a bigger problem: billing, inventory and accounting were operating as separate islands.
That experience changed the way Rajiv looked at business software.
He no longer wanted software simply to generate invoices. He wanted a system capable of helping him understand the business.
For many growing businesses, that is the real transition from basic digitisation to meaningful business management.
Why New Friends Colony Market Businesses Need Integrated Information
Businesses serving New Friends Colony and surrounding South Delhi areas may handle diverse customer requirements and a wide range of products.
Whether the business sells garments, electronics, furnishings, accessories, food products, lifestyle goods or other merchandise, inventory visibility becomes increasingly important as the number of transactions grows.
Suppose an owner wants to determine which products should be reordered.
Inventory information can reveal the available quantity and stock movement.
But the owner may also want to know:
How much cash is currently available?
Which customers have outstanding balances?
Which suppliers need to be paid this week?
How much money is already tied up in inventory?
Which products contribute meaningfully to revenue?
These questions require inventory and accounting information to work together.
Why Amar Colony Market Businesses Should Look Beyond Billing
Amar Colony Market has a strong retail environment, particularly for businesses dealing with products that can vary by size, style, category, design or other attributes.
For such businesses, a billing application alone may become restrictive.
Fast billing is important, but a business also needs visibility after the invoice has been generated.
Owners need to understand stock movement, purchases, returns, customer balances, supplier payments, expenses and profitability.
This is where the distinction between billing software and complete accounting and inventory management becomes important.
How Integrated Accounting and Inventory Can Reduce Duplicate Work
One of the biggest operational problems with separate systems is duplicate data entry.
Imagine that the sales team creates an invoice in one application. The inventory team then updates stock in another system, while the accountant records the transaction again in accounting software.
The same business event may be entered multiple times.
Every additional manual entry introduces an opportunity for:
Typing errors
Missing invoices
Incorrect quantities
Duplicate transactions
Wrong customer balances
Delayed reporting
Reconciliation differences
An integrated system can reduce this duplication by allowing a transaction to affect the relevant records together.
When properly configured, a sales invoice can update the customer's account, sales value, taxes and stock quantity as part of the same transaction.
Where TallyPrime Fits Into Business Management
For many Indian businesses, TallyPrime is used for accounting, inventory management and GST-related business processes.
Depending on the organisation's requirements and configuration, businesses can maintain accounting ledgers alongside inventory information instead of keeping completely separate records.
This can be particularly useful for retailers, wholesalers, distributors, traders and SMEs that want financial and inventory information within a common business system.
A business should still configure its masters, taxation, inventory structure and user processes according to its actual requirements.
Software does not automatically fix poor data-entry practices. The quality of reports depends heavily on the quality and consistency of the information entered.
Inventory Management Helps Prevent Overstocking
Running out of popular products can lead to lost sales.
But excessive inventory creates another problem.
Money invested in slow-moving stock cannot easily be used for rent, salaries, supplier payments, marketing or new products.
Imagine a retailer investing ₹5 lakh in merchandise.
If ₹2 lakh worth of those products barely move for several months, the business has significant working capital locked in stock.
Good inventory reporting can help owners identify slow-moving and fast-moving products so that purchasing decisions can be based on actual movement rather than assumptions.
Accounting Software Helps You Understand Profitability
High sales do not necessarily mean high profit.
A store might generate impressive monthly revenue while simultaneously experiencing high purchase costs, discounts, operating expenses and outstanding customer payments.
This is why accounting reports matter.
Business owners should be able to examine sales together with purchases, direct costs, indirect expenses, receivables, payables and other financial information.
Inventory tells the owner what is on the shelf.
Accounting helps explain what the business is earning.
Together, they provide a much more complete picture.
GST Makes Accurate Records Even More Important
GST compliance adds another reason to maintain structured transaction data.
Sales and purchases can affect GST reporting, input tax credit, output tax liability and reconciliation.
Businesses should ensure that invoices, GSTIN details, tax rates, transaction classifications and other relevant information are entered accurately.
An integrated accounting system can make it easier to maintain structured records for GST-related reporting, but businesses should still regularly review their data and reconcile it with applicable GST records and returns.
Technology can simplify compliance, but accuracy remains the responsibility of the business.
Signs Your Business May Need More Than Basic Inventory Software
A growing business should review its software setup if employees frequently maintain parallel Excel sheets, stock figures do not match physical inventory, customer outstanding amounts are difficult to determine, supplier balances require manual calculation, GST data requires extensive correction, or management reports take hours to prepare.
Another warning sign is dependency on one person.
If only one employee knows how to combine information from multiple spreadsheets and applications to understand the actual business position, the process carries operational risk.
Centralising information can reduce this dependency.
What Should Businesses Consider Before Choosing Software?
Do not select business software only because it has a long feature list.
Start with actual business requirements.
A small service company with virtually no physical stock may need strong accounting capabilities but very little inventory functionality.
A retailer with thousands of SKUs may require detailed stock management alongside accounting.
A wholesaler may need strong receivable, payable, inventory and order-management capabilities.
A multi-location operation may need additional controls and consolidated reporting.
Businesses should consider transaction volume, number of users, product complexity, GST requirements, reporting needs, security, backups, remote-working requirements, scalability and support before finalising a solution.
The Bigger Benefit: Better Decisions
The most valuable result of integrating inventory and accounting is not simply faster data entry.
It is better decision-making.
Imagine starting the morning and being able to answer:
What sold yesterday?
Which products need replenishment?
Which customers owe money?
Which supplier payments are approaching?
What is the current stock position?
What are the major expenses?
How is the business performing?
When business information is organised, owners spend less time collecting numbers and more time acting on them.
For businesses in New Friends Colony Market and Amar Colony Market, that visibility can become increasingly valuable as competition and transaction volumes increase.
Inventory Software or Accounting Software: Which One Should You Choose?
There is no single answer for every business.
If your primary requirement is detailed warehouse and stock control, specialised inventory software may be appropriate.
If your organisation primarily provides services, accounting software may be sufficient.
But if your business buys, stores and sells goods while also managing GST, customers, suppliers, receivables and financial reporting, an integrated accounting and inventory system may offer significant operational advantages.
The correct choice should be based on workflow rather than simply software popularity.
Why Implementation Matters as Much as Software
Buying software is only the beginning.
Businesses need to define stock groups, item names, units, tax classifications, ledgers, customer and supplier records, user access and internal procedures correctly.
Historical data may also need to be migrated or cleaned.
Employees require training.
Reports need to be reviewed after implementation.
Without these steps, even powerful software can produce confusing results.
A properly planned implementation helps ensure that the system reflects how the business actually operates.
Conclusion
The difference between inventory software and accounting software becomes clearer when you consider the questions each system answers.
Inventory software focuses primarily on goods: what came in, what went out, what remains and how stock is moving.
Accounting software focuses on financial activity: what was earned, what was spent, what customers owe, what the business owes and what the financial position looks like.
For growing businesses in New Friends Colony Market and Amar Colony Market, the bigger opportunity is often to connect these two areas.
An integrated accounting and inventory environment can reduce duplicate data entry, improve stock visibility, strengthen financial reporting and help management make decisions using more consistent information.
In 2026, business software should do more than replace registers and spreadsheets. It should help business owners understand what is happening across stock, sales, money and compliance.
The goal is not simply digital accounting.
The goal is better business control.
Powered by Binarysoft Technologies
Authorized Tally Partner
Binarysoft Technologies provides Tally-related solutions, implementation, support and business accounting assistance for organisations looking to improve their accounting and inventory-management processes.
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact us: +91 7428779101, 9205471661
Email us: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Mon–Fri
Frequently Asked Questions
What is the main difference between inventory software and accounting software?
Inventory software primarily tracks products, quantities and stock movement. Accounting software records the financial impact of business transactions, including sales, purchases, receipts, payments, expenses, receivables, payables and financial reports.
Does a retail shop need both inventory and accounting software?
A retailer generally needs visibility into both stock and finances. Whether that requires two separate applications or one integrated solution depends on the size, complexity and workflow of the business.
CA. Vivaan Deshmukh focuses on financial reporting, audit procedures, and taxation. He shares practical insights on accounting software, business process optimization, and compliance management for SMEs and growing enterprises.