Call CA Tally HelpDesk
+91 9205471661,
7428779101
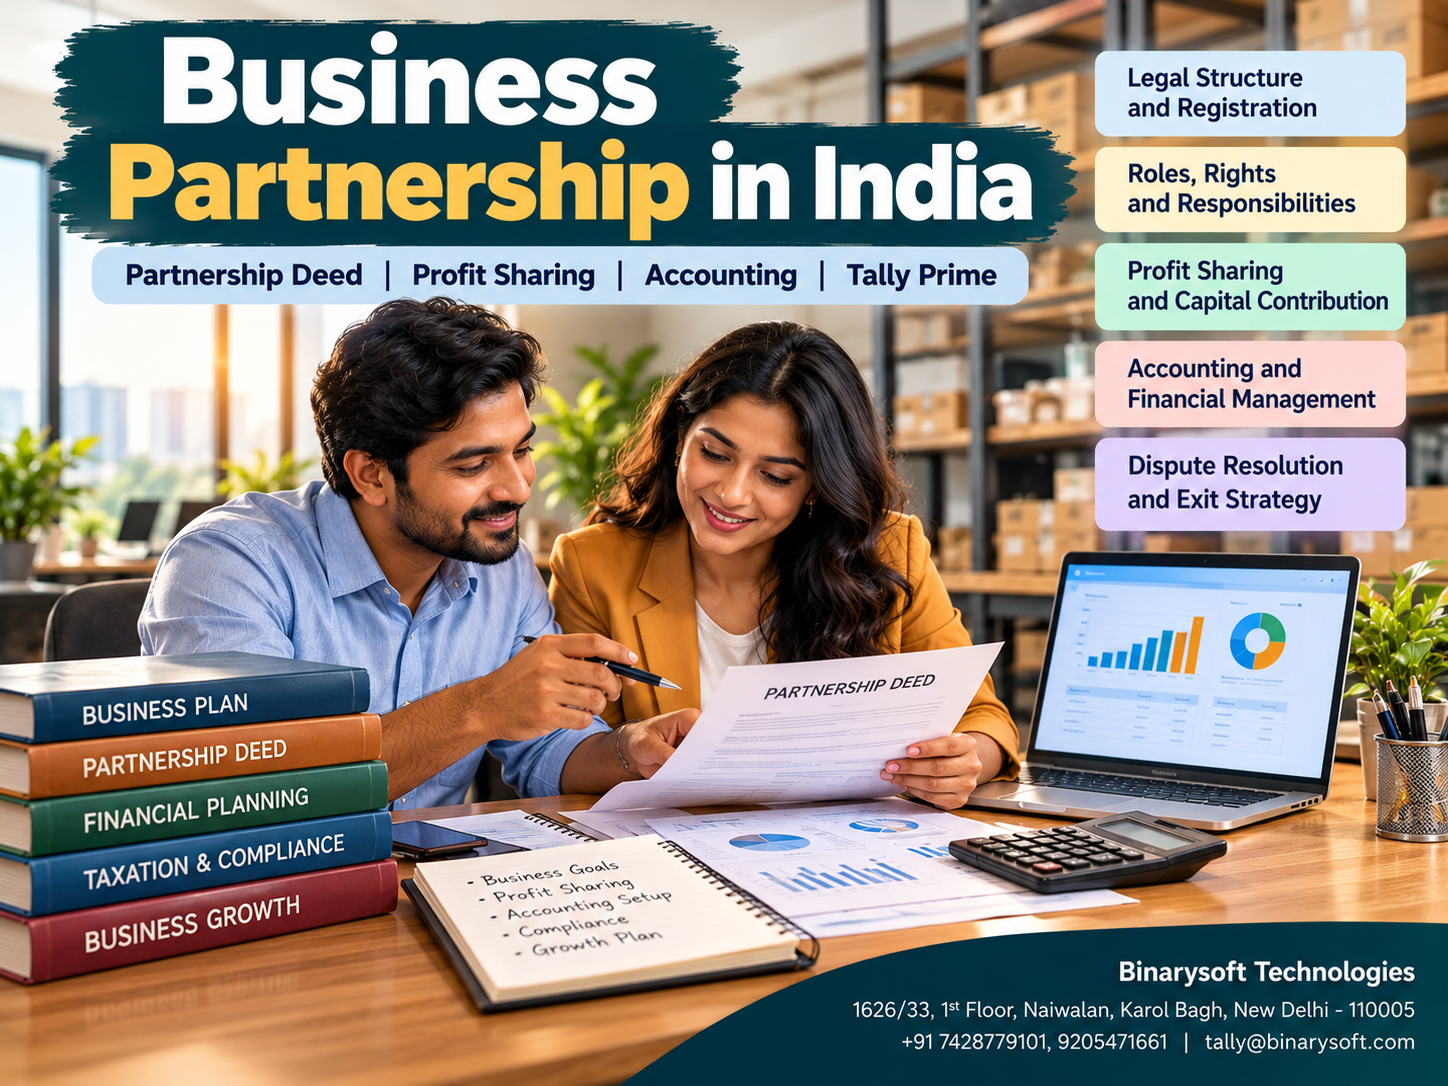
Introduction: Why Choosing the Right Business Partner Matters in 2026
A business partnership often begins with a simple conversation between friends, family members or professional associates. One person has a business idea, another has financial resources, and both believe they can achieve more together.
But turning that understanding into a successful business requires careful planning.
In India's increasingly competitive business environment, entrepreneurs must consider changing customer expectations, financial risks, digital accounting requirements and regulatory responsibilities before forming a partnership.
A partnership can combine different skills, distribute operational responsibilities and provide additional capital. At the same time, disagreements about money, decision-making and profit distribution can damage even long-standing relationships.
Understanding partnership laws, preparing a comprehensive partnership deed and maintaining transparent financial records are essential steps toward building a sustainable enterprise.
This article explores the important elements of business partnerships, common mistakes entrepreneurs should avoid and how Tally Prime can support accurate partnership accounting.
The Story of Two Friends Who Almost Lost Their Business and Friendship
Amit and Rohit had been friends since college. For years, they dreamed of opening an electronics distribution business in Delhi.
Amit understood suppliers, inventory and market demand. Rohit had experience managing finances and customer relationships.
They invested their savings and rented a small warehouse. During the first year, orders increased and the business appeared successful.
However, neither partner had clearly documented their responsibilities.
Amit believed that his daily involvement justified a larger share of profits. Rohit felt that his higher capital investment entitled him to greater financial returns.
Disagreements gradually became personal.
One evening, after an argument over a supplier payment, Amit told Rohit that perhaps they should close the business.
Both remembered the sacrifices their families had made to support their dream.
Instead of ending the partnership, they consulted a professional adviser, documented their financial arrangements and introduced structured accounting.
They established clear responsibilities, agreed on withdrawal limits and began reviewing monthly financial reports together.
Their relationship improved because financial decisions were no longer based on assumptions.
This is a fictional illustrative story based on common partnership challenges.
The lesson is that trust may bring partners together, but clarity, communication and financial discipline help keep them together.
1. What Is a Business Partnership?
A business partnership is a commercial relationship in which two or more persons agree to share the profits of a business carried on by all or any of them acting for all.
In India, traditional partnership firms are principally governed by the Indian Partnership Act, 1932.
A partnership may combine capital, professional knowledge, management experience and business relationships.
For example, one partner may manage purchasing and inventory while another handles finance, marketing and customer relationships.
Unlike a private limited company or LLP, a traditional partnership firm generally does not provide its partners with limited liability protection.
Understanding this distinction is important before selecting the business structure.
2. Types of Business Partnerships in India
Entrepreneurs should understand the different arrangements available before establishing a business together.
General partnership
A traditional partnership generally involves partners sharing business responsibilities and liabilities according to the partnership agreement and applicable law.
Partners may be jointly and severally liable for obligations of the firm.
Partnership at will
A partnership at will exists where the agreement does not specify a fixed duration or a provision determining the partnership's termination.
It may be dissolved through the legally prescribed notice process.
Particular partnership
A particular partnership may be established for a specific undertaking or project.
Its duration and termination depend on the agreement and applicable law.
Limited Liability Partnership
An LLP is a separate legal structure governed by the Limited Liability Partnership Act, 2008.
It generally offers limited liability protection and a different compliance framework from an ordinary partnership firm.
Entrepreneurs should compare formation costs, liability exposure, compliance requirements and growth plans before choosing between a traditional partnership and an LLP.
3. Choose the Right Business Partner
Selecting a partner is one of the most important decisions an entrepreneur can make.
A reliable partner should contribute more than financial resources.
Compatibility in business values, risk tolerance, communication style and long-term objectives is equally important.
Before entering a partnership, discuss expected working hours, capital requirements, borrowing policies and expansion plans.
Partners should also examine each other's relevant business experience and financial commitments.
Friendship or family relationships alone should not determine partnership suitability.
Successful partnerships are built on complementary skills, mutual respect and clearly documented expectations.
4. Prepare a Comprehensive Partnership Deed
A partnership deed is a written agreement describing the relationship between partners.
Although partnership arrangements may arise without a written deed, a properly drafted agreement can prevent significant misunderstandings.
A comprehensive deed should address:
-
Firm name and principal business address
-
Names and details of partners
-
Nature and objectives of the business
-
Capital contributions
-
Profit-and-loss sharing ratios
-
Partner remuneration and interest arrangements
-
Responsibilities and management authority
-
Banking and borrowing permissions
-
Rules for withdrawals and additional capital
-
Admission, retirement and removal of partners
-
Dispute resolution and dissolution procedures
The deed should also specify how business assets, intellectual property and confidential information will be handled.
Applicable stamp duty and execution requirements depend on the relevant jurisdiction.
Professional legal assistance is recommended when preparing the agreement.
5. Decide Capital Contributions Before Starting
Partners may contribute different amounts of capital.
Some may contribute cash, while others provide eligible assets or other agreed resources.
For example, two entrepreneurs may establish a trading firm with the following initial capital:
|
Partner
|
Capital contribution
|
|---|
|
Amit
|
₹6,00,000
|
|
Rohit
|
₹4,00,000
|
|
Total capital
|
₹10,00,000
|
A larger capital contribution does not automatically establish a larger profit share.
Profit distribution depends on the partnership agreement and applicable legal provisions.
Partners should document the valuation of non-cash contributions and the treatment of additional capital.
How Tally Prime helps: Separate partner capital ledgers can be maintained to record contributions, adjustments and balances.
6. Establish a Clear Profit-and-Loss Sharing Ratio
Profit sharing is frequently a source of disagreement.
Partners should agree on their respective shares before business operations begin.
For example, suppose a firm earns ₹12,00,000 in distributable profit after relevant accounting adjustments.
Illustrative profit-sharing arrangement
Partner A — 60%
₹7,20,000
Partner B — 40%
₹4,80,000
Assumes the amount is available for appropriation and no further adjustments are required.
Profit-sharing arrangements should distinguish between accounting profit, taxable income, partner remuneration and amounts actually withdrawn.
Tally Prime can help maintain the accounting entries needed for agreed profit appropriations.
7. Understand Partnership Firm Registration
Traditional partnership firm registration is handled through the relevant Registrar of Firms under applicable state procedures.
Registration under the Indian Partnership Act is not universally compulsory merely to establish a traditional partnership. However, non-registration creates significant restrictions on enforcing certain contractual rights through courts.
Entrepreneurs should therefore seriously consider registration.
Common documentation may include the partnership deed, prescribed application, partner identification and business address details.
The firm may also require PAN, GST registration, trade licences or other registrations depending on its activities.
An LLP follows a separate incorporation process.
8. Understand Partner Rights and Responsibilities
Each partner should understand their legal and operational responsibilities.
Partners generally owe duties of good faith, honest dealing and proper disclosure in relation to partnership affairs.
They should maintain accurate records and avoid unauthorized use of business assets.
Management authority should be clearly allocated.
For example, one partner may approve supplier purchases while another manages banking and financial reporting.
Significant borrowing, asset disposal or expansion decisions can require joint approval under the agreement.
Clearly defining authority reduces the possibility of unauthorized commitments.
9. Partnership Firm Taxation and GST Compliance
Traditional partnership firms are taxed under provisions applicable to firms rather than individual slab rates.
The applicable income-tax framework generally provides a 30% base tax rate for partnership firms, with applicable surcharge and cess.
Partner remuneration and interest may be deductible subject to statutory limits, deed authorization and other conditions.
Profit shares and partner remuneration have different tax treatments.
GST registration requirements depend on turnover, business activities, location and other applicable provisions.
Partnership firms must also evaluate TDS, advance tax and audit obligations.
A qualified Chartered Accountant should review the firm's specific compliance requirements.
10. Why Financial Transparency Is Essential
A partnership becomes vulnerable when one partner controls financial information without appropriate oversight.
Both partners should have access to agreed financial reports.
Monthly reviews should cover sales, expenses, profitability, outstanding payments, inventory and bank balances.
Partners should establish authorization limits and maintain supporting documents for major transactions.
Tally Prime can support financial transparency through structured ledgers, voucher records, reporting and configurable user permissions.
However, effective internal controls still require management discipline and periodic review.
11. Case Study One: Two Retail Partners Resolve Profit-Sharing Disputes
Illustrative case study — fictional business and figures
Two entrepreneurs established a wholesale stationery business in Delhi.
One invested ₹8 lakh, while the other invested ₹5 lakh and managed daily operations.
Initially, they agreed verbally to share profits equally.
After the first profitable year, disagreements emerged over working responsibilities and capital contributions.
The partners consulted an adviser and documented their agreed arrangements in a revised partnership deed.
They established separate capital accounts, formalized remuneration where appropriate and introduced monthly financial reviews.
Using Tally Prime, they recorded capital contributions, business expenses and agreed appropriation entries.
Result: The partners gained clearer financial visibility and reduced disputes over withdrawals and profit distribution.
Key lesson: Written agreements and transparent accounting are essential even when partners have a strong personal relationship.
12. Case Study Two: A Manufacturing Partnership Improves Cash Flow
Illustrative case study — fictional business and figures
A small packaging manufacturing partnership in Faridabad experienced increasing sales but struggled with delayed customer payments.
One partner managed production while the other handled sales.
Without consolidated reporting, they frequently disagreed about available cash.
The business introduced bill-wise receivables tracking, purchase records and regular bank reconciliation.
Partners began reviewing outstanding invoices together and established clearer credit policies.
In this illustrative scenario, overdue customer balances decreased from ₹15 lakh to ₹9 lakh over several months.
Result: Better working capital visibility supported supplier payments and reduced financial disagreements.
Key lesson: Accurate financial information helps partners make decisions based on business realities rather than personal assumptions.
13. How Tally Prime Helps Manage Partnership Accounting
Tally Prime can support partnership firms through organized accounting and business reporting.
Partner capital accounts
Separate capital ledgers can record partner contributions, capital adjustments and closing balances.
Partner drawings
Withdrawals can be recorded separately from ordinary business expenses.
This distinction helps prevent confusion between personal withdrawals and operating expenditure.
Profit-and-loss reporting
The Profit & Loss Account helps partners understand business performance before profit appropriation.
Inventory management
Stock reports, purchase records and inventory valuation support businesses dealing in physical goods.
GST accounting
GST-enabled invoices, purchase transactions and tax reports help maintain compliance-related records.
Receivables and payables
Outstanding reports help partners monitor customer collections and supplier commitments.
Banking and financial controls
Bank reconciliation and transaction reporting support accurate cash and bank balances.
Partner-wise financial review
Appropriate ledgers and accounting entries can support analysis of partner capital, drawings, remuneration and profit appropriations.
Tally Prime does not automatically determine legal profit-sharing rights or guarantee compliance with partnership agreements. These matters require correct configuration, accounting judgment and professional review.
14. Common Partnership Mistakes Entrepreneurs Should Avoid
Many partnership disputes can be prevented through early planning.
Common mistakes include entering business without a written agreement, mixing personal and business funds, failing to document withdrawals and giving unclear management authority.
Another serious mistake is ignoring liability exposure.
In a traditional partnership, one partner's actions within the scope of business authority can create obligations affecting other partners.
Entrepreneurs should also avoid relying entirely on verbal financial reports.
Regular accounting reviews, documented approvals and transparent communication can significantly reduce misunderstandings.
15. Plan for Partner Retirement, Exit and Dissolution
Partnerships can change as business circumstances evolve.
A partner may retire, become unable to continue working or wish to pursue another opportunity.
The partnership deed should specify how such situations will be handled.
Important provisions include business valuation, settlement of capital balances, treatment of goodwill, responsibility for liabilities and procedures for admitting replacement partners.
The agreement should also address dispute resolution and circumstances requiring dissolution.
A planned exit process protects the business and helps preserve relationships.
16. Checklist Before Starting a Partnership Business
|
Important requirement
|
Recommended action
|
|---|
|
Partner selection
|
Evaluate experience, values and financial commitments
|
|
Business objectives
|
Agree on long-term goals
|
|
Capital contribution
|
Document each partner's investment
|
|
Partnership deed
|
Prepare a legally reviewed agreement
|
|
Profit sharing
|
Define ratios and remuneration
|
|
Registration
|
Review applicable firm registration procedures
|
|
Tax compliance
|
Obtain necessary registrations
|
|
Banking
|
Establish authorized signatories
|
|
Accounting
|
Implement structured bookkeeping
|
|
Exit planning
|
Define retirement and dissolution terms
|
Completing these steps before launching the business can reduce financial uncertainty and future disagreements.
Conclusion: A Successful Partnership Needs More Than Trust
Starting a business with a partner can create valuable opportunities for growth, shared investment and stronger management.
However, long-term success depends on clearly defined responsibilities, transparent financial arrangements and effective communication.
A comprehensive partnership deed, suitable business structure and reliable accounting practices provide an important foundation.
Tally Prime can support partnership management through capital accounts, expense tracking, financial reporting, inventory control and GST-related workflows.
Entrepreneurs should remember that a successful partnership is not simply about sharing profits. It is about sharing responsibilities, respecting agreements and making informed decisions together.
When partners combine mutual trust with professional discipline, they improve their chances of building a business that can withstand challenges and grow sustainably.
Powered by Binarysoft Technologies
Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact Us: +91 7428779101, 9205471661
Email: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Monday to Friday
Frequently Asked Questions
What is a partnership business in India?
A partnership is a business relationship between two or more persons who agree to share profits from a business carried on by all or any of them acting for all.
Is a written partnership deed compulsory?
A traditional partnership can arise without a written deed, but a properly drafted agreement is strongly recommended to document responsibilities, financial arrangements and dispute-resolution procedures.
How are profits divided between partners?
Profits are distributed according to the agreed profit-sharing ratio. In the absence of an agreement to the contrary, applicable partnership law generally provides for equal sharing of profits and contribution to losses.
Are partners personally liable for business debts?
In a traditional partnership, partners generally face joint and several liability for firm obligations. LLPs have a different liability framework.
CA. Anand Tirpathi is a Chartered Accountant with experience in statutory compliance, internal controls, and accounting process optimization. He has advised multiple businesses on improving operational efficiency through structured accounting and inventory systems. His writing focuses on clarity, compliance, and risk reduction for MSMEs.