Call CA Tally HelpDesk
+91 9205471661,
7428779101
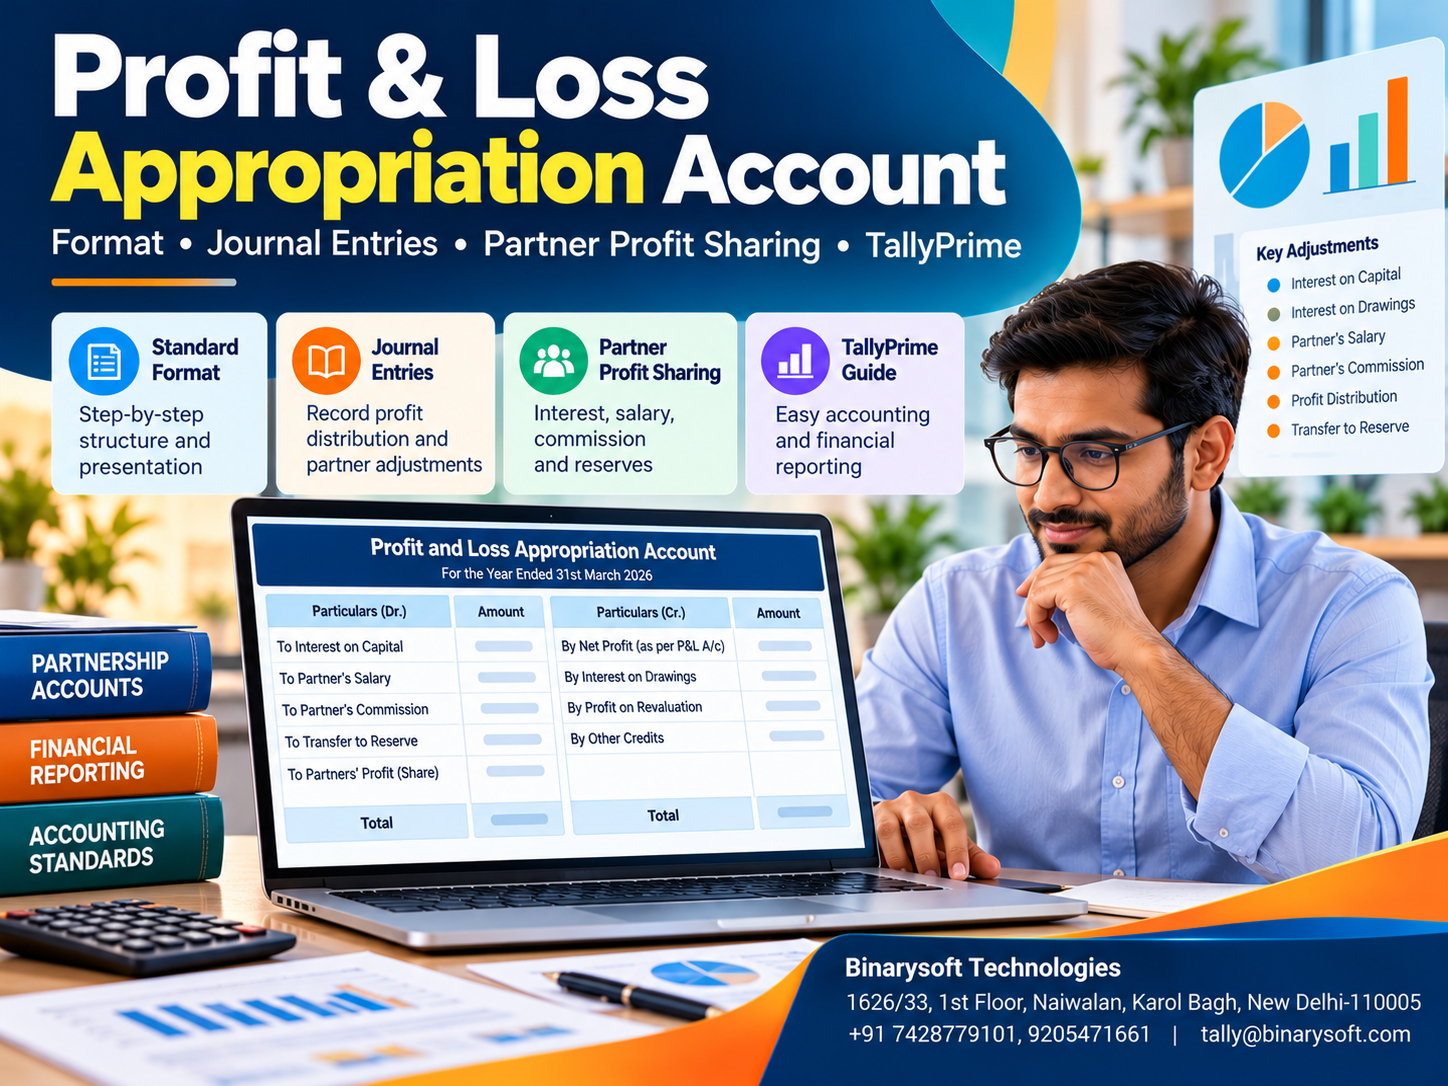
Introduction: Why Profit Appropriation Matters for Every Partnership Business
A partnership business may generate impressive sales, maintain loyal customers and report healthy annual profits. Yet disagreements can arise when partners discover that they have different expectations about how those profits should be distributed.
In 2026, Indian partnership firms operate in an increasingly competitive environment where accurate accounting, transparent financial reporting and clearly documented agreements are essential for sustainable growth. Whether running a wholesale trading company, manufacturing unit, consultancy or family enterprise, partners must understand how the firm's earnings are allocated.
The Profit and Loss Appropriation Account plays an important role in this process.
It helps partnership firms calculate and record the distribution of profit among partners after considering agreed items such as interest on capital, partners' remuneration, commission and interest on drawings.
Unlike the regular Profit and Loss Account, which determines business profitability, the appropriation account explains how the available profit is allocated according to the partnership agreement.
Without a structured process, businesses may face disputes, inaccurate partner balances and difficulties preparing year-end financial statements.
TallyPrime can help firms maintain partner ledgers, record appropriation journal entries and review financial reports.
This guide explains the Profit and Loss Appropriation Account format, calculations, journal entries, practical examples and how TallyPrime supports accurate partnership accounting.
1. What Is a Profit and Loss Appropriation Account?
A Profit and Loss Appropriation Account is an account commonly prepared by partnership firms to show how the firm's net profit or loss is allocated among partners.
It is generally prepared after determining the profit available from the Profit and Loss Account.
The appropriation account considers items specified in the partnership deed, including:
-
Interest on partners' capital.
-
Partners' salary or remuneration.
-
Partners' commission.
-
Interest charged on drawings.
-
Transfer to reserves, where agreed.
-
Remaining profit or loss distributed among partners.
For example, a partnership firm earns a net profit of ₹8,00,000 during the financial year.
The partnership agreement provides for interest on capital and remuneration to working partners.
After accounting for these appropriations, the remaining profit is divided according to the agreed profit-sharing ratio.
The appropriation account provides a structured explanation of these calculations.
2. Objectives of Preparing a Profit and Loss Appropriation Account
The primary objective is to ensure that partners receive the amounts determined under their partnership agreement.
It also helps distinguish business profitability from the allocation of profits.
A well-maintained appropriation account improves transparency by showing how the final distributable amount was calculated.
This becomes particularly important when partners have different capital contributions, responsibilities and remuneration arrangements.
The account also supports accurate maintenance of partners' capital or current accounts.
When prepared consistently, it provides useful documentation for annual financial reviews and partnership discussions.
3. Format of Profit and Loss Appropriation Account
A traditional Profit and Loss Appropriation Account is presented in a T-shaped format, with debit and credit sides.
Profit and Loss Appropriation Account for the Year Ended 31 March 2026
|
Debit (Dr.) particulars
|
Amount (₹)
|
Credit (Cr.) particulars
|
Amount (₹)
|
|---|
|
To Interest on Capital
|
80,000
|
By Net Profit transferred from P&L A/c
|
8,00,000
|
|
To Partners' Salary
|
1,20,000
|
By Interest on Drawings
|
20,000
|
|
To Partners' Commission
|
40,000
|
|
|
|
To General Reserve
|
60,000
|
|
|
|
To Partners' Profit Share
|
5,20,000
|
|
|
|
Total
|
8,20,000
|
Total
|
8,20,000
|
This is an illustrative format. The items included depend on the partnership deed and applicable accounting treatment.
The credit side includes the net profit available for appropriation and interest on drawings.
The debit side includes agreed appropriations and the residual profit transferred to partners.
4. Difference Between Profit and Loss Account and Appropriation Account
Although the names are similar, the two accounts serve different purposes.
|
Basis
|
Profit and Loss Account
|
Profit and Loss Appropriation Account
|
|---|
|
Main purpose
|
Determines net profit or loss
|
Allocates profit or loss among partners
|
|
Prepared
|
Before appropriation
|
After determining available profit
|
|
Major items
|
Revenue and operating expenses
|
Interest on capital, remuneration and profit shares
|
|
Main users
|
Businesses generally
|
Primarily partnership firms
|
|
Result
|
Net profit or loss
|
Distribution of available profit or loss
|
|
Relationship
|
Provides the starting profit figure
|
Uses that figure for appropriation
|
For example, rent, electricity, employee salaries and other ordinary business expenses are generally recorded when determining operating profit.
Partners' remuneration treated as an appropriation under the partnership accounting arrangement is shown separately in the appropriation account.
Its tax treatment and financial reporting classification may require separate consideration.
5. Important Components of the Appropriation Account
Interest on Capital
Interest on capital is an amount allowed to partners for capital invested in the business, where provided by the partnership deed.
Suppose a partner contributes ₹10,00,000 and is entitled to 6% annual interest.
Interest on capital = ₹10,00,000 × 6% = ₹60,000.
If capital changes during the year, the calculation may require time-based adjustments.
Partners' Salary
Some partners actively manage business operations and receive remuneration according to the partnership agreement.
For example, a working partner may be entitled to ₹15,000 per month.
Annual remuneration = ₹15,000 × 12 = ₹1,80,000.
Partners' Commission
A partnership agreement may provide commission based on sales, profits or another agreed measure.
Commission based on profit before charging commission is calculated differently from commission based on profit after charging commission.
The exact formula should follow the deed.
Interest on Drawings
Partners may withdraw money from the business for personal use.
If the partnership agreement requires interest on drawings, the amount is charged to the relevant partner.
The calculation depends on withdrawal dates, amounts and the agreed interest rate.
Profit-Sharing Ratio
The remaining profit is distributed according to the ratio specified in the partnership deed.
For example, a 3:2 ratio means one partner receives three-fifths and the other receives two-fifths of the distributable profit.
6. An Emotional Story: When Profit Distribution Threatened a Family Partnership
For nearly twenty years, brothers Arvind and Deepak operated a wholesale textile business in Chandni Chowk, Delhi.
Their father had established the business with a small investment and a belief that family unity was more valuable than any commercial success.
Arvind handled purchases, supplier negotiations and inventory.
Deepak managed customers, collections and daily operations.
Over time, the business expanded into several wholesale markets.
However, the brothers never developed a consistent method for recording partners' remuneration, drawings and profit distribution.
Arvind had contributed more capital, while Deepak spent more hours managing the business.
Both believed their contributions deserved greater recognition.
When the accountant announced the annual profit, disagreements began.
Arvind argued that his larger investment should earn interest.
Deepak insisted that his management responsibilities justified additional remuneration.
Neither brother had a clear statement explaining how the final profit should be allocated.
Their father, now retired, watched the disagreement with growing concern.
One evening, he asked both sons to meet him at the original shop.
He showed them an old photograph of the three of them standing beside the business's first delivery vehicle.
Then he said, "I built this business so you could work together, not so money would separate you."
The brothers decided to review their partnership agreement and accounting records.
With professional assistance, they established clearer appropriation procedures and separate partner accounts.
The accountant configured the relevant ledgers in TallyPrime and prepared a transparent statement showing interest on capital, remuneration, drawings and remaining profit.
The figures did not eliminate every disagreement, but both brothers could understand how the amounts had been calculated.
Gradually, their business discussions became more constructive.
For their father, the greatest achievement was not the improved accounting report. It was seeing his sons planning the future together again.
This fictional story illustrates how transparent profit appropriation can support trust and communication in family partnerships.
7. Step-by-Step Calculation of Profit and Loss Appropriation
Consider a partnership firm operated by Rahul and Amit.
The partnership agreement specifies the following:
|
Particulars
|
Amount
|
|---|
|
Net profit before appropriation
|
₹10,00,000
|
|
Rahul's capital
|
₹8,00,000
|
|
Amit's capital
|
₹6,00,000
|
|
Interest on capital
|
5% annually
|
|
Rahul's annual remuneration
|
₹1,20,000
|
|
Amit's annual remuneration
|
₹80,000
|
|
Interest on drawings — Rahul
|
₹10,000
|
|
Interest on drawings — Amit
|
₹5,000
|
|
Profit-sharing ratio
|
3:2
|
Step 1: Calculate Interest on Capital
Rahul: ₹8,00,000 × 5% = ₹40,000
Amit: ₹6,00,000 × 5% = ₹30,000
Total interest on capital = ₹70,000.
Step 2: Calculate Partners' Remuneration
Rahul's remuneration = ₹1,20,000
Amit's remuneration = ₹80,000
Total remuneration = ₹2,00,000.
Step 3: Add Interest on Drawings
Rahul's interest on drawings = ₹10,000
Amit's interest on drawings = ₹5,000
Total = ₹15,000.
Step 4: Determine Residual Profit
Net profit: ₹10,00,000
Add interest on drawings: ₹15,000
Less interest on capital: ₹70,000
Less remuneration: ₹2,00,000
Residual profit = ₹7,45,000
Step 5: Distribute Remaining Profit
Rahul's share = ₹7,45,000 × 3/5 = ₹4,47,000
Amit's share = ₹7,45,000 × 2/5 = ₹2,98,000
Final Appropriation Account
|
Debit particulars
|
Amount (₹)
|
Credit particulars
|
Amount (₹)
|
|---|
|
To Rahul — Interest on Capital
|
40,000
|
By Net Profit
|
10,00,000
|
|
To Amit — Interest on Capital
|
30,000
|
By Rahul — Interest on Drawings
|
10,000
|
|
To Rahul — Remuneration
|
1,20,000
|
By Amit — Interest on Drawings
|
5,000
|
|
To Amit — Remuneration
|
80,000
|
|
|
|
To Rahul — Profit Share
|
4,47,000
|
|
|
|
To Amit — Profit Share
|
2,98,000
|
|
|
|
Total
|
10,15,000
|
Total
|
10,15,000
|
This example assumes sufficient profit and no additional restrictions or appropriations.
8. Journal Entries for Profit and Loss Appropriation Account
Transfer of Net Profit
Profit & Loss A/c Dr. ₹10,00,000
To Profit & Loss Appropriation A/c ₹10,00,000
Interest on Capital
Profit & Loss Appropriation A/c Dr. ₹70,000
To Rahul's Current A/c ₹40,000
To Amit's Current A/c ₹30,000
Partners' Remuneration
Profit & Loss Appropriation A/c Dr. ₹2,00,000
To Rahul's Current A/c ₹1,20,000
To Amit's Current A/c ₹80,000
Interest on Drawings
Rahul's Current A/c Dr. ₹10,000
Amit's Current A/c Dr. ₹5,000
To Profit & Loss Appropriation A/c ₹15,000
Distribution of Residual Profit
Profit & Loss Appropriation A/c Dr. ₹7,45,000
To Rahul's Current A/c ₹4,47,000
To Amit's Current A/c ₹2,98,000
These entries assume the fixed capital method. Under the fluctuating capital method, relevant adjustments are normally recorded through partners' capital accounts.
9. How TallyPrime Helps Manage Profit and Loss Appropriation
TallyPrime provides accounting features that help partnership firms record profit appropriation entries and maintain individual partner balances.
Businesses can create separate capital and current ledgers for each partner.
Journal vouchers can record interest on capital, remuneration, interest on drawings and profit allocations.
Ledger statements allow accounting teams to review individual partner transactions.
The Trial Balance helps verify overall debit and credit balances.
Financial reports provide useful information for reviewing the firm's profitability and financial position.
However, TallyPrime does not automatically interpret partnership deed clauses or calculate every profit appropriation arrangement.
Businesses must determine the correct amounts and record them using appropriate accounting entries.
10. Step-by-Step Guide to Recording Profit Appropriation in TallyPrime
Partnership firms can maintain appropriation entries through a structured accounting process.
Step 1: Review the partnership deed. Confirm the profit-sharing ratio, interest rates, remuneration arrangements and other relevant clauses.
Step 2: Create partner ledgers. Create separate capital accounts and, where the fixed capital method is followed, current accounts for each partner.
Step 3: Review the annual net profit. Examine the Profit & Loss Account and verify necessary year-end adjustments.
Step 4: Calculate appropriation amounts. Prepare a working statement showing interest on capital, remuneration, interest on drawings and residual profit.
Step 5: Create appropriate ledgers. Establish a suitable Profit & Loss Appropriation ledger and any additional ledgers required by the firm's accounting structure.
Step 6: Record journal entries. Use journal vouchers to transfer profit and record the approved appropriations.
Step 7: Verify partner balances. Review capital or current account ledgers and ensure the entries agree with the appropriation statement.
Step 8: Examine financial reports. Check the Trial Balance and Balance Sheet to verify the overall accounting position.
Menu names and ledger grouping choices may vary according to TallyPrime configuration and the firm's accounting requirements.
11. Case Study One: A Delhi Wholesale Partnership Improves Profit Distribution
Illustrative case study based on common partnership accounting challenges.
Business Background
A wholesale electrical goods distributor in Bhagirath Palace, Delhi, operated with three partners.
Each partner had invested different amounts, and two partners actively managed business operations.
Challenges
The company distributed profits informally without consistently recording interest on capital and working partner remuneration.
This created disagreements during annual accounting reviews.
Solution
The firm reviewed its partnership deed and introduced a structured Profit and Loss Appropriation Account.
Partner capital and current accounts were configured in TallyPrime.
The accountant prepared a detailed appropriation statement and recorded the necessary journal entries.
Business Outcome
Partners gained clearer visibility into their financial entitlements.
Annual profit allocation became easier to verify.
The company also improved documentation for future partnership discussions.
Key lesson: Transparent appropriation records help partners understand how profits are allocated.
12. Case Study Two: A Manufacturing Partnership Simplifies Year-End Accounting
Illustrative case study demonstrating organized profit appropriation.
Business Background
A manufacturing partnership in Faridabad produced industrial components for customers across North India.
The firm had four partners with different capital contributions and management responsibilities.
Challenges
Interest on capital, drawings and partner remuneration were maintained in separate spreadsheets.
The accounting team spent considerable time reconciling partner balances at year-end.
Solution
The business introduced separate partner ledgers and standardized appropriation journal entries in TallyPrime.
A year-end checklist was created to verify profit allocations and supporting calculations.
Business Outcome
The firm reduced manual reconciliation work.
Partner balances became easier to review, and management gained clearer financial information.
The accounting department also established more consistent procedures.
Key lesson: Integrated accounting records can simplify partnership profit distribution and financial reporting.
13. Common Mistakes in Profit and Loss Appropriation Accounts
Businesses sometimes confuse ordinary operating expenses with profit appropriations.
Another common mistake is calculating interest on capital without considering the applicable time period.
Incorrect profit-sharing ratios can also create significant discrepancies.
Some firms forget to charge interest on drawings even when the partnership deed requires it.
Others distribute profits before completing necessary year-end accounting adjustments.
To reduce these errors, businesses should verify the partnership agreement, prepare detailed working statements and reconcile partner balances before finalizing accounts.
14. Profit Appropriation and Income Tax Considerations
Accounting profit appropriation and income tax treatment are not necessarily identical.
For example, interest and remuneration paid to partners may be subject to conditions and limits under applicable income tax provisions.
Amounts recorded as appropriations in partnership accounts are not automatically deductible for tax purposes.
Businesses should also review applicable requirements for tax deduction at source on relevant payments to partners, including provisions effective from April 2025.
The firm's legal classification, partnership deed and prevailing tax rules determine the appropriate treatment.
A qualified tax professional should review these matters before finalizing tax computations.
15. How TallyPrime on Cloud Helps Partnership Firms
Partnership firms operating from multiple locations may benefit from remote access to accounting records.
With suitable hosting infrastructure and licensing, authorized partners and accounting employees can access their TallyPrime environment from different locations.
This can support coordinated bookkeeping and financial reviews.
Cloud hosting may also assist with centralized access and backup planning.
However, firms should evaluate data security, user permissions, connectivity and recovery procedures before implementation.
16. Why Professional Accounting Support Matters
Profit appropriation involves more than recording a few journal entries.
Businesses must interpret partnership agreements, calculate adjustments and maintain accurate partner balances.
Binarysoft Technologies assists firms with TallyPrime implementation, ledger configuration, accounting workflows, financial reporting and employee training.
Professional support can help businesses establish consistent accounting procedures.
Legal interpretation of partnership agreements and tax treatment should be reviewed by qualified professionals.
Conclusion
The Profit and Loss Appropriation Account is an important tool for partnership financial management.
It explains how the firm's profit is allocated after considering agreed interest, remuneration, commission and other appropriations.
A properly prepared appropriation account improves transparency and helps maintain accurate partner balances.
TallyPrime supports this process through ledger management, journal vouchers and financial reporting.
However, correct calculations, a clearly documented partnership agreement and regular reconciliation remain essential.
With structured accounting practices, partnership firms can reduce financial misunderstandings and strengthen long-term business relationships.
Accurate profit appropriation is not only about dividing earnings. It is about maintaining fairness, transparency and trust among business partners.
Powered by Binarysoft Technologies
Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact Us: +91 7428779101, 9205471661
Email: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Monday to Friday
Frequently Asked Questions
How can Binarysoft Technologies help with partnership accounting?
Binarysoft Technologies can assist with TallyPrime configuration, partner ledger setup, journal voucher workflows, financial reporting, software upgrades and employee training.
Are partners' remuneration and interest automatically deductible for income tax?
No. Tax deductibility depends on applicable legal conditions, limits and documentation. Accounting treatment alone does not determine tax deductibility.
Can TallyPrime prepare partnership appropriation entries?
TallyPrime supports the ledgers and journal vouchers needed to record appropriation entries. The business must calculate and verify the appropriate amounts.
Why is interest on drawings credited to the appropriation account?
Interest on drawings represents an amount charged to partners under the partnership agreement and is commonly credited to the appropriation account.
CA. Dhruv Bhandekar works with businesses on bookkeeping controls, GST reporting, and month-end accounting processes. His focus is on creating structured financial workflows that improve accuracy and reduce reconciliation issues.