Call CA Tally HelpDesk
+91 9205471661,
7428779101
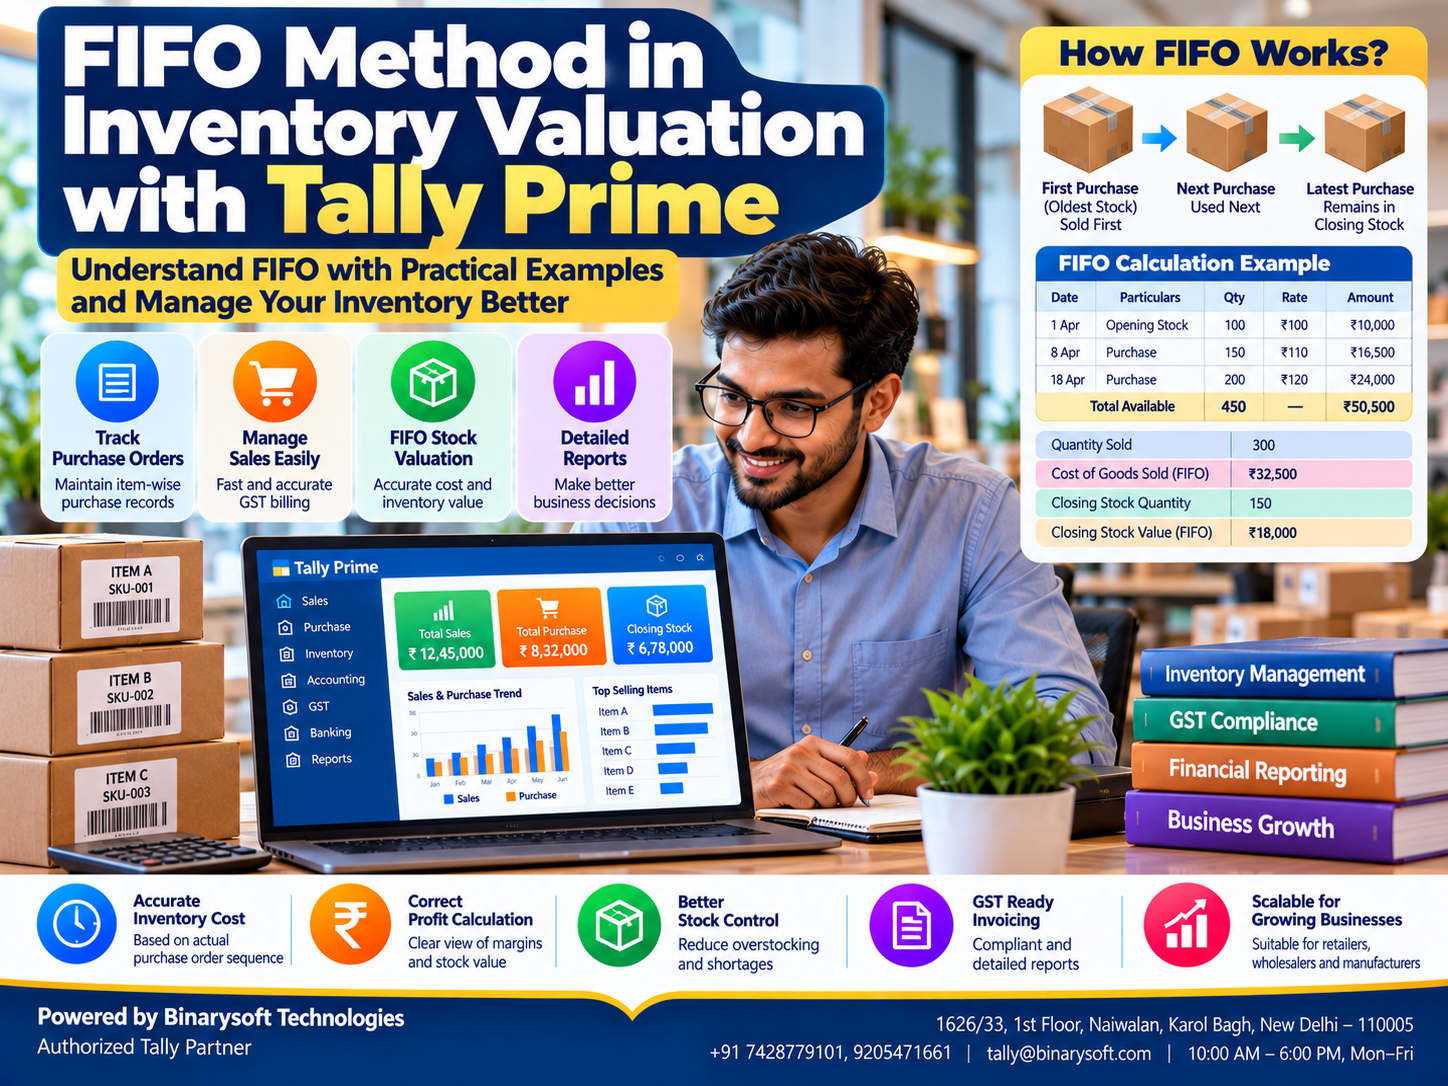
Introduction: Why FIFO Inventory Valuation Matters for Indian Businesses
Every business that purchases, stores, manufactures, or sells physical goods needs to understand the value of its inventory.
For retailers, wholesalers, distributors, and manufacturers, inventory is often one of the largest investments in working capital. Yet many business owners focus primarily on sales figures without understanding how stock valuation affects profitability.
Consider a wholesale trader purchasing the same product at different prices throughout the month. When some units are sold, which purchase cost should be assigned to those sales?
Should the business use the oldest purchase price, the latest purchase price, or an average cost?
The answer depends on the inventory valuation method used.
FIFO, or First In, First Out, is a widely used inventory valuation method that assumes the earliest purchased or produced inventory is sold or consumed first for cost calculation purposes.
Under FIFO, older inventory costs are assigned to cost of goods sold before newer costs.
As a result, closing inventory generally reflects the cost of more recent purchases.
This method is particularly relevant for businesses that maintain products purchased at changing prices.
FIFO can also complement stock rotation practices, although accounting valuation and physical stock movement are not necessarily identical.
Tally Prime supports FIFO-based stock valuation and provides inventory reports that help businesses review stock quantities, inventory values, and related accounting information.
This guide explains FIFO with detailed calculations, practical business examples, advantages, limitations, and guidance for using the method in Tally Prime.
The Shopkeeper's Story: When Rising Purchase Prices Created a Financial Surprise
In Delhi's Chawri Bazar, Mohan operated a wholesale hardware business that his father had established many years earlier.
The shop supplied tools, fittings, and industrial accessories to small retailers and contractors.
Mohan carefully monitored daily sales and customer payments.
However, he rarely examined how changing purchase prices affected inventory valuation.
One year, supplier prices began increasing.
A particular hardware component that previously cost ₹100 per unit was now being purchased for ₹125.
Mohan continued selling products and believed the business was earning healthy profits.
But when his accountant prepared the year-end financial statements, Mohan became confused.
The value of unsold stock was different from what he had expected.
He worried that someone had made a mistake.
His father noticed his concern and asked what had happened.
Mohan explained that the same product had been purchased at different prices and he did not understand which cost should be used for the remaining inventory.
His father encouraged him to examine the records carefully rather than assume something was wrong.
The accountant explained the FIFO method using actual purchase batches.
He demonstrated how older purchase costs were assigned to goods sold and newer purchase costs remained in closing inventory.
For the first time, Mohan understood the relationship between purchase prices, stock valuation, and reported profitability.
He also realized that higher accounting profits did not automatically mean the business had more cash available.
Mohan began reviewing inventory valuation alongside sales margins and supplier payments.
The experience changed how he managed his business.
Instead of looking only at turnover, he started paying attention to the true financial impact of stock movement.
This is an illustrative story inspired by common challenges faced by Indian trading businesses.
1. What Is the FIFO Method of Inventory Valuation?
FIFO stands for First In, First Out.
It is a cost-flow assumption used to determine the cost of inventory sold or consumed and the value of inventory remaining at the end of an accounting period.
Under FIFO, the cost of the oldest available inventory is assigned first when calculating the cost of goods sold.
The remaining inventory is valued using the costs of newer purchases.
For example, suppose a retailer purchases 100 units at ₹50 each and later purchases another 100 units at ₹60 each.
If the retailer sells 120 units, FIFO assigns the cost of the first 100 units at ₹50 and the next 20 units at ₹60.
The remaining 80 units are valued at ₹60 each.
FIFO is a valuation assumption. It does not necessarily prove that the oldest physical units were actually dispatched first.
That distinction is important for businesses managing warehouses, perishable products, or batch-controlled goods.
2. FIFO Formula for Inventory Valuation
The basic inventory relationship is:
\[ \text{Closing Inventory}=\text{Opening Inventory}+\text{Purchases}-\text{Cost of Goods Sold} \]
For a trading business, this formula uses inventory costs rather than sales revenue.
Under FIFO, the cost of goods sold is calculated by assigning the earliest available purchase costs to the quantity sold.
The closing stock value is then calculated from the remaining cost layers.
In simple terms:
FIFO Cost of Goods Sold = Cost of the oldest available inventory units assigned to sales
FIFO Closing Stock = Cost of the inventory units remaining after older cost layers are exhausted
The following example demonstrates the calculation.
3. Practical FIFO Inventory Valuation Example with Calculation
Consider a wholesale trader selling electrical accessories.
During April, the business purchases the same product at three different prices.
|
Date
|
Transaction
|
Quantity
|
Unit Cost
|
Total Cost
|
|---|
|
1 April
|
Opening Stock
|
100
|
₹100
|
₹10,000
|
|
8 April
|
Purchase
|
150
|
₹110
|
₹16,500
|
|
18 April
|
Purchase
|
200
|
₹120
|
₹24,000
|
| |
Total Available
|
450
|
|
₹50,500
|
Suppose the business sells 300 units during the month.
Under FIFO, the oldest inventory costs are assigned first.
Step 1: Calculate the cost of 300 units sold
|
Inventory Layer
|
Quantity Sold
|
Unit Cost
|
Cost
|
|---|
|
Opening Stock
|
100
|
₹100
|
₹10,000
|
|
8 April Purchase
|
150
|
₹110
|
₹16,500
|
|
18 April Purchase
|
50
|
₹120
|
₹6,000
|
|
Total
|
300
|
|
₹32,500
|
Therefore:
\[ \text{FIFO COGS} = ₹32,500 \]
Step 2: Calculate closing inventory
Total available quantity = 450 units.
Quantity sold = 300 units.
Closing quantity = 150 units.
The remaining 150 units belong to the latest purchase cost layer of ₹120 per unit.
\[ 150 \times ₹120 = ₹18,000 \]
Total Inventory Cost
₹50,500
Cost of Goods Sold
₹32,500
Closing Stock Quantity
150 units
Closing Stock Value
₹18,000
The calculation can also be verified:
₹50,500 − ₹32,500 = ₹18,000.
This demonstrates how FIFO assigns earlier purchase costs to sales while leaving more recent costs in closing inventory.
4. Interactive FIFO Calculator: Try Your Own Example
Change the quantity sold to see how the oldest cost layers are consumed first.
Inventory cost layers
Layer 1: 100 units at ₹100
100 sold
Layer 2: 150 units at ₹110
150 sold
Layer 3: 200 units at ₹120
50 sold
Cost of goods sold
₹32,500
Closing inventory value
₹18,000
Reset example
5. How FIFO Affects Cost of Goods Sold and Profitability
FIFO can significantly affect reported profitability when purchase prices change.
During periods of rising prices, older inventory generally has a lower purchase cost than newer inventory.
Because FIFO assigns older costs to goods sold, the resulting cost of goods sold may be lower than under a weighted-average method.
Lower cost of goods sold generally produces a higher gross profit, assuming sales revenue and other factors remain unchanged.
However, this does not mean the business has earned additional cash.
Reported profit and actual cash flow are different financial measures.
During periods of falling purchase prices, the relationship may reverse.
FIFO may assign relatively higher historical costs to sales while closing inventory reflects more recent, lower-cost purchases.
Business owners should therefore interpret profitability alongside cash flow, stock movement, and current replacement costs.
6. FIFO vs Weighted Average Cost Method
FIFO and weighted average cost are both recognized approaches to inventory cost allocation for ordinarily interchangeable inventory under applicable accounting standards.
Consider the earlier example.
Total inventory quantity = 450 units.
Total inventory cost = ₹50,500.
Weighted average unit cost:
\[ ₹50,500 \div 450 = ₹112.22 \]
For 300 units sold, the weighted-average cost of goods sold is approximately ₹33,666.67.
The closing inventory value is approximately ₹16,833.33.
|
Particulars
|
FIFO
|
Weighted Average
|
|---|
|
Quantity Sold
|
300
|
300
|
|
Cost of Goods Sold
|
₹32,500
|
₹33,666.67
|
|
Closing Stock Quantity
|
150
|
150
|
|
Closing Stock Value
|
₹18,000
|
₹16,833.33
|
In this rising-price example, FIFO produces a lower cost of goods sold and a higher closing stock value.
The difference arises from the cost allocation method, not from a change in the physical quantity of inventory.
The weighted-average illustration assumes a periodic average for the entire set of purchases. A moving-average calculation can produce different results depending on transaction timing.
7. FIFO vs LIFO: Important Differences
LIFO stands for Last In, First Out.
Under LIFO, the latest inventory costs are assigned first to goods sold.
FIFO does the opposite by assigning the earliest costs first.
During rising purchase prices, LIFO generally produces higher cost of goods sold and lower closing inventory values than FIFO.
However, LIFO is not permitted under Ind AS 2 or AS 2 for inventories governed by those standards.
Indian businesses preparing financial statements under applicable Indian accounting standards should follow the inventory cost formulas and measurement requirements relevant to their reporting framework.
FIFO should also be applied consistently to inventories of similar nature and use, subject to the applicable accounting requirements.
8. Advantages of the FIFO Inventory Valuation Method
FIFO offers several practical advantages.
First, it provides a systematic way to allocate historical inventory costs to sales.
Second, during rising-price periods, closing inventory generally reflects more recent purchase costs.
Third, the method can be relatively straightforward to understand when purchase quantities and prices are recorded accurately.
Fourth, FIFO is commonly used for inventories where older goods are physically dispatched before newer goods.
Fifth, it supports consistent inventory valuation and financial reporting when applied appropriately.
However, these advantages depend on reliable transaction records and correct accounting treatment.
FIFO should not be selected solely because it produces a preferred profit figure.
9. Limitations of FIFO Inventory Valuation
FIFO also has limitations.
During inflationary periods, historical costs assigned to sales may be lower than current replacement costs.
This can result in reported gross profits that appear higher than the margins available on replacement purchases.
Businesses maintaining numerous purchase batches may require software to calculate inventory costs efficiently.
Errors in opening stock, purchase dates, quantities, or rates can affect valuation results.
FIFO also does not automatically ensure correct physical stock rotation.
Warehouse procedures must separately address product expiry, damage, obsolescence, and storage conditions.
Finally, accounting standards may require inventory to be measured at the lower of cost and net realizable value, so the FIFO-calculated cost is not always the final carrying amount.
10. How to Configure FIFO Inventory Valuation in Tally Prime
Tally Prime supports FIFO as a stock valuation method.
Businesses can configure inventory valuation according to their accounting requirements and review the resulting stock reports.
The general process is as follows:
-
Open the relevant company in Tally Prime.
-
Navigate to the stock-item master creation or alteration screen.
-
Select the stock item requiring FIFO valuation.
-
Open the applicable stock-item configuration or valuation settings.
-
Select FIFO as the valuation method where the option is available.
-
Save the stock-item configuration.
-
Record purchases using the correct quantities, dates, and rates.
-
Record sales or consumption through appropriate inventory-linked vouchers.
-
Open the Stock Summary or relevant inventory valuation report.
-
Review the calculated closing stock value and investigate any unexpected differences.
The exact navigation and availability of valuation settings may vary according to the installed release and configuration.
Before changing valuation methods in a live company, businesses should take a verified backup and assess the effect on financial reporting.
A change in valuation method may require accounting review, particularly where previously reported inventory values could be affected.
11. Practical Example of FIFO in Tally Prime
Consider a retailer selling packaged electrical components.
The business records the following purchases:
|
Purchase Date
|
Quantity
|
Rate
|
Value
|
|---|
|
5 June
|
50
|
₹200
|
₹10,000
|
|
12 June
|
80
|
₹220
|
₹17,600
|
|
20 June
|
70
|
₹240
|
₹16,800
|
|
Total
|
200
|
|
₹44,400
|
Suppose 120 units are sold after all three purchases have been recorded.
Under FIFO:
50 units × ₹200 = ₹10,000
70 units × ₹220 = ₹15,400
Total cost of goods sold = ₹25,400.
The remaining inventory consists of 10 units at ₹220 and 70 units at ₹240.
Closing stock value:
\[ (10 \times ₹220)+(70 \times ₹240)=₹19,000 \]
When the relevant transactions are correctly recorded and FIFO valuation is applied, Tally Prime can calculate the inventory value from the recorded cost layers.
The business can review the result through its inventory reports.
12. Case Study One: FIFO Valuation for an FMCG Distributor in Delhi
Illustrative case study.
An FMCG distributor in Delhi supplied packaged food products and household consumables to retailers.
The company purchased goods at different rates throughout the month.
The challenge
Management found it difficult to determine the value of closing stock because supplier prices changed frequently.
The accounting team used inconsistent manual calculations, creating differences between inventory schedules and financial reports.
The solution
The business standardized its stock masters and adopted an appropriate FIFO valuation approach in its accounting records.
Purchase transactions were recorded with accurate quantities, dates, and costs.
Employees were also instructed to follow suitable physical stock rotation procedures for products with limited shelf lives.
The outcome
The distributor developed a more consistent approach to calculating inventory costs.
Management gained better visibility into closing stock values and the relationship between purchase prices and gross profit.
The case demonstrates the importance of accurate cost records and consistent inventory valuation.
13. Case Study Two: FIFO Inventory Valuation for a Hardware Wholesaler
Illustrative case study.
A hardware wholesaler in Chawri Bazar purchased industrial fittings, fasteners, and electrical accessories from several suppliers.
Purchase prices changed during the year because of variations in material and transportation costs.
The challenge
The owner compared current selling prices with the latest purchase costs but did not understand why reported gross margins differed.
The business also maintained manual inventory valuation schedules that were difficult to reconcile.
The solution
The accounting team reviewed purchase records and introduced a consistent FIFO valuation process for suitable inventory items.
Tally Prime was used to maintain stock-item records, purchase vouchers, sales transactions, and inventory reports.
Management began reviewing gross profit alongside closing inventory values and current replacement costs.
The outcome
The business improved the consistency of its inventory valuation process.
The owner gained a clearer understanding of how historical purchase costs influenced reported profitability.
The example illustrates why stock valuation should be considered alongside sales performance and working capital management.
14. FIFO and Physical Stock Rotation: Are They the Same?
FIFO accounting and FIFO warehouse rotation are related but different concepts.
FIFO inventory valuation is a method of assigning purchase or production costs to goods sold and closing inventory.
Physical FIFO rotation means dispatching or using older goods before newer goods.
A business can apply FIFO valuation even when its warehouse does not physically dispatch the oldest items first.
However, businesses selling products that may deteriorate over time often benefit from organized stock rotation.
For products with expiry dates, First Expired, First Out (FEFO) may be more appropriate operationally.
FEFO prioritizes products approaching expiry, regardless of their purchase date.
Businesses should choose warehouse procedures according to product characteristics, safety requirements, and operational needs.
15. FIFO, GST and Financial Reporting in India
FIFO affects the calculation of inventory cost and cost of goods sold.
It does not directly determine the GST rate charged on a sales invoice.
GST treatment depends on the nature of the goods, transaction, classification, and applicable law.
For financial reporting, inventory valuation can influence gross profit, closing stock, and the carrying amount of current assets.
Under applicable Indian accounting standards, inventories are generally measured at the lower of cost and net realizable value, subject to relevant scope exceptions.
FIFO determines the allocation of historical costs, but additional adjustments may be necessary when inventory is damaged, obsolete, or expected to sell below cost.
Businesses should consult qualified accounting professionals when applying accounting standards or making material valuation changes.
16. Best Practices for Accurate FIFO Inventory Valuation
Businesses should adopt disciplined procedures to maintain reliable FIFO calculations.
-
Record purchases promptly with correct dates, quantities, and costs.
-
Verify opening stock quantities and values.
-
Avoid duplicate stock-item masters.
-
Use consistent units of measurement.
-
Record sales, returns, and stock adjustments accurately.
-
Review negative stock and backdated transaction situations.
-
Reconcile physical inventory with accounting records.
-
Examine obsolete, damaged, and slow-moving goods.
-
Maintain verified backups before major configuration changes.
-
Review inventory valuation policies with accounting professionals.
These practices help reduce valuation differences and improve the reliability of financial statements.
17. How FIFO Supports Better Business Decisions
FIFO can help management understand how historical inventory costs affect reported margins.
During rising purchase prices, businesses may observe that the cost assigned to current sales is lower than the latest replacement cost.
This distinction is important when making pricing decisions.
For example, a wholesaler may report a healthy gross profit on goods purchased several months earlier.
However, replenishing the same stock at current prices may require significantly more working capital.
Management should therefore review both accounting margins and current supplier prices.
Tally Prime's inventory and financial reports can support this analysis by providing structured transaction information.
The objective is not simply to calculate closing stock correctly but to understand how inventory costs influence business performance.
Conclusion
The FIFO method of inventory valuation is an important accounting technique for retailers, wholesalers, manufacturers, and distributors.
By assigning older inventory costs to goods sold first, FIFO provides a systematic approach to calculating cost of goods sold and closing stock values.
The practical examples demonstrate how purchase quantities and changing prices affect inventory valuation.
During rising-price periods, FIFO generally produces lower cost of goods sold and higher closing inventory values than a periodic weighted-average calculation, assuming other factors remain unchanged.
Tally Prime supports FIFO inventory valuation and helps businesses maintain purchase records, sales transactions, stock quantities, and inventory reports.
The two illustrative case studies show how consistent valuation practices can improve financial reporting and management understanding.
Accurate inventory valuation is not simply an accounting requirement. It helps business owners understand profitability, protect working capital, and make informed purchasing and pricing decisions.
With reliable records, consistent accounting policies, and appropriate professional review, FIFO can become an effective part of inventory and financial management.
Powered by Binarysoft Technologies Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact us: +91 7428779101, 9205471661
Email us: tally@binarysoft.com (10:00 AM – 6:00 PM, Mon–Fri)
Frequently Asked Questions
How can businesses improve FIFO accuracy in Tally Prime?
Maintain correct stock masters, record purchases and sales promptly, verify opening balances, review backdated entries, reconcile inventory, and check valuation reports regularly.
Can businesses change their inventory valuation method?
Changes may be possible, but businesses should assess accounting policy requirements, consistency, reporting implications, and professional advice before doing so.
Can FIFO closing stock value be reduced?
Yes. Applicable accounting standards may require inventory to be written down to net realizable value when it is lower than cost.
Can FIFO be used for manufacturing inventory?
Yes. FIFO may be used for suitable raw materials, components, and finished goods where consistent with the applicable accounting requirements.
CA. Shivesh Khandelwaal is a practicing Chartered Accountant experienced in accounting automation, compliance management, and audit support. He has worked with trading and distribution businesses to improve inventory visibility and financial reporting. His articles focus on real-world applicability.









