Call CA Tally HelpDesk
+91 9205471661,
7428779101
Introduction: Why Closing Inventory Is More Important Than You Think
Imagine running a successful retail business where sales are increasing every month. Customers are satisfied, suppliers are delivering products regularly, and your warehouse remains busy.
However, when your accountant prepares the financial statements, an unexpected problem appears.
The business has purchased large quantities of goods, but nobody knows the exact value of the unsold inventory.
Some products remain in the warehouse, while others have been sold, damaged or returned.
Without accurate closing inventory information, calculating business profitability becomes difficult.
Closing inventory represents the value of goods and materials remaining unsold or unused at the end of an accounting period.
For Indian manufacturers, retailers, wholesalers and distributors, accurate closing stock calculations are essential for determining cost of goods sold, preparing financial statements and managing working capital.
Tally Prime helps businesses maintain inventory records, calculate stock values and generate reports that support informed financial decisions.
This guide explains the closing inventory formula, its practical applications and common mistakes businesses should avoid.
1. What Is Closing Inventory?
Closing inventory, also called ending inventory or closing stock, is the value of goods and materials remaining with a business at the end of a reporting period.
It may include trading goods, raw materials, work-in-progress and finished products.
For example, an electrical distributor purchases 1,000 switches during a month and sells 700.
Assuming there was no opening stock or other movement, 300 switches remain.
The value assigned to those 300 switches represents closing inventory for that product.
The quantity and monetary value are different measurements.
Businesses must calculate both accurately.
Closing inventory is generally presented as a current asset in the balance sheet.
Its valuation also affects the calculation of cost of goods sold and gross profit.
2. What Is the Closing Inventory Formula?
The basic closing inventory formula for a trading business is:
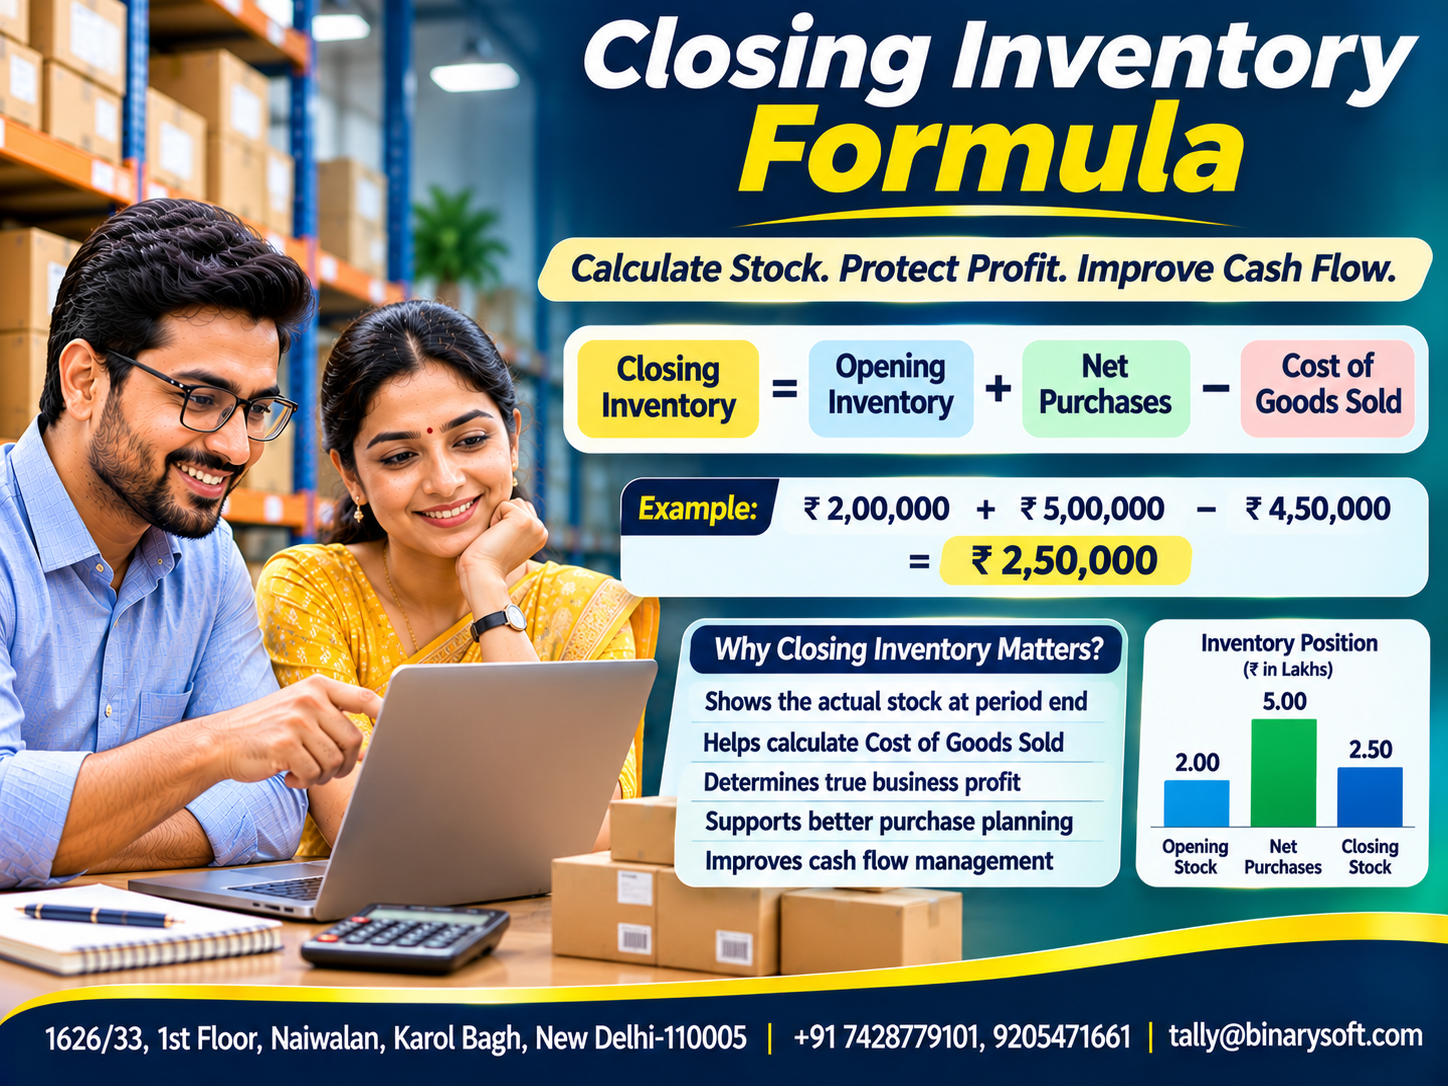
Closing Inventory = Opening Inventory + Net Purchases − Cost of Goods Sold
Where:
Opening Inventory: Value of inventory available at the beginning of the period.
Net Purchases: Cost of inventory purchased during the period, adjusted for applicable returns, discounts and directly attributable acquisition costs.
Cost of Goods Sold: Cost assigned to inventory sold during the period.
For a simple trading business, this formula provides a useful reconciliation.
Manufacturing businesses may require additional calculations for raw materials, work-in-progress and finished goods.
An important distinction is that sales revenue must not be subtracted directly from inventory cost.
Sales revenue includes the selling margin, whereas cost of goods sold represents the cost of the products sold.
3. Closing Inventory Formula with Example
Consider a hypothetical electronics distributor.
Opening Inventory: ₹2,00,000
Net Purchases: ₹5,00,000
Cost of Goods Sold: ₹4,50,000
Using the formula:
Closing Inventory = ₹2,00,000 + ₹5,00,000 − ₹4,50,000
Closing Inventory = ₹2,50,000
This means the business has ₹2,50,000 of inventory remaining at the end of the period, subject to physical verification and applicable valuation adjustments.
The calculation helps management understand how much money remains invested in unsold goods.
It also provides information for preparing financial statements.
4. Closing Inventory Quantity Formula
Businesses must calculate inventory quantities separately from monetary values.
The basic formula is:
Closing Quantity = Opening Quantity + Stock Inward − Stock Outward
Suppose:
Opening Stock: 500 units
Purchases: 300 units
Sales: 450 units
Closing Quantity:
500 + 300 − 450 = 350 units.
Therefore, the business has 350 units remaining.
Other transactions, such as returns, production consumption, damage and adjustments, must also be considered.
The final monetary value depends on the applicable inventory costing method.
5. Why Is Closing Inventory Important?
Accurate closing inventory affects several aspects of business management.
Financial Reporting
Closing inventory is reported as an asset and influences financial statements.
Gross Profit Calculation
The value of closing stock affects cost of goods sold.
Purchasing Decisions
Management can identify unnecessary stock accumulation.
Cash Flow Management
Excess inventory may indicate that working capital is tied up in unsold products.
Stock Verification
Comparing recorded inventory with physical quantities helps identify discrepancies.
Business Planning
Closing stock information supports future purchasing and production decisions.
For growing businesses, accurate inventory valuation is therefore both an accounting requirement and a management tool.
6. How Closing Inventory Affects Cost of Goods Sold
Cost of goods sold represents the cost assigned to products sold during an accounting period.
For a straightforward trading business:
COGS = Opening Inventory + Net Purchases − Closing Inventory
Suppose:
Opening Inventory: ₹3,00,000
Net Purchases: ₹8,00,000
Closing Inventory: ₹2,50,000
COGS:
₹3,00,000 + ₹8,00,000 − ₹2,50,000
COGS = ₹8,50,000
If net sales revenue is ₹12,00,000:
Gross Profit = ₹12,00,000 − ₹8,50,000
Gross Profit = ₹3,50,000
This demonstrates why closing inventory must be calculated correctly.
An incorrect closing stock value can distort reported profitability.
7. What Happens When Closing Inventory Is Overvalued?
Overvaluation occurs when inventory is recorded at a value higher than the amount permitted by the applicable accounting policy.
Suppose actual closing inventory should be ₹4,00,000.
However, the accounts report ₹4,50,000.
The difference is ₹50,000.
Assuming other figures remain unchanged, the overvaluation reduces reported cost of goods sold by ₹50,000.
This increases reported gross profit by the same amount.
Consequently, the business may appear more profitable than it actually is.
Overvaluation can result from incorrect quantities, inappropriate costing methods or failure to recognize necessary inventory write-downs.
8. What Happens When Closing Inventory Is Undervalued?
Undervaluation occurs when inventory is recorded below its appropriate value.
Suppose actual closing inventory should be ₹5,00,000.
However, the accounts show ₹4,60,000.
The difference is ₹40,000.
Assuming other figures remain unchanged, reported cost of goods sold increases by ₹40,000.
This reduces reported gross profit.
Incorrect inventory valuation can therefore mislead management.
Businesses should maintain consistent valuation policies and investigate significant discrepancies before finalizing accounts.
9. Common Inventory Valuation Methods
The value of closing inventory depends on the costing method adopted.
FIFO: First-In, First-Out
FIFO assumes that earlier inventory costs are assigned to goods sold first.
Remaining inventory is valued using more recent purchase costs.
Weighted Average Cost
This method calculates an average cost for interchangeable inventory items.
The average is used to assign costs according to the applicable accounting approach.
Specific Identification
This method tracks the actual cost of identifiable inventory items.
It may be appropriate for unique or high-value products that are not ordinarily interchangeable.
For financial reporting in India, the selected method must comply with applicable accounting requirements.
LIFO is not an acceptable inventory cost formula under AS 2 or Ind AS 2.
Businesses should seek professional guidance when selecting valuation policies.
10. FIFO Closing Inventory Calculation Example
Consider a retailer purchasing the same product at different prices.
First Purchase: 100 units at ₹500 each.
Second Purchase: 100 units at ₹550 each.
Total Quantity: 200 units.
Suppose 120 units are sold.
Closing Quantity:
200 − 120 = 80 units.
Under FIFO, the first 100 units purchased and 20 units from the second purchase are assigned to sales.
The remaining 80 units are valued at ₹550 each.
Closing Inventory:
80 × ₹550 = ₹44,000.
Closing Inventory Value = ₹44,000
This example assumes no other movements or valuation adjustments.
11. Weighted Average Closing Inventory Example
Using the same purchases:
100 units × ₹500 = ₹50,000.
100 units × ₹550 = ₹55,000.
Total Purchase Cost:
₹1,05,000.
Total Quantity:
200 units.
Weighted Average Cost:
₹1,05,000 ÷ 200 = ₹525 per unit.
If 120 units are sold, 80 remain.
Closing Inventory:
80 × ₹525 = ₹42,000.
Closing Inventory Value = ₹42,000
The FIFO and weighted average calculations produce different values because the purchase prices differ.
Businesses should follow their selected accounting policy consistently.
12. An Emotional Story: The Closing Stock Mistake That Changed a Family Business
For sixteen years, Manoj operated a wholesale stationery business in Delhi.
He began with a small shop and gradually expanded into supplying schools, offices and local retailers.
His wife managed accounts, while his son handled customer enquiries.
Every year, Manoj focused on increasing sales.
He believed that higher revenue automatically meant better financial health.
However, one financial year ended differently.
The accountant requested the closing stock value.
Manoj estimated the amount based on recent purchases.
There had been no complete physical verification.
Several damaged products remained in the warehouse, while some customer returns had not been recorded correctly.
When the accountant reviewed the figures, the inventory records did not match the actual stock.
The reported profit was unreliable.
Manoj became worried.
His business had supplier payments approaching, and he had promised his son that they would expand the warehouse.
One evening, his son found him sitting alone in the office.
“Papa, why are you looking so worried?” he asked.
Manoj replied, “I worked hard to increase sales, but I never understood how important the stock remaining in our warehouse was.”
His son suggested improving inventory records.
The family began verifying physical quantities, reviewing damaged products and maintaining proper stock transactions.
They also introduced monthly closing stock reviews.
Gradually, the financial reports became more dependable.
Purchasing decisions improved because management could identify excess inventory.
At the end of the following year, Manoj reviewed the accounts with greater confidence.
His son asked whether the business was finally ready for expansion.
Manoj smiled.
“This time, we will expand because the numbers support the decision, not because we are guessing.”
For Manoj, accurate closing inventory was not merely an accounting calculation. It became a way to protect his family's future and make responsible business decisions.
This story is fictional and illustrates a common business challenge.
13. Case Study One: Retailer Improves Closing Stock Accuracy
Business Background
A hypothetical household goods retailer manages approximately 1,500 products.
The Challenge
Inventory records contain missing sales returns and unrecorded damaged goods.
The closing inventory value differs from physical stock verification.
The Solution
The business introduces monthly stock reconciliation and consistent transaction recording using Tally Prime.
Illustrative Outcome
Initial Unexplained Inventory Difference: ₹1,20,000.
Revised Difference: ₹30,000.
Reduction:
₹1,20,000 − ₹30,000 = ₹90,000.
Percentage Reduction:
₹90,000 ÷ ₹1,20,000 × 100 = 75%.
Business Lesson
Regular inventory reconciliation can improve financial reporting reliability.
This case study is hypothetical.
14. Case Study Two: Manufacturer Improves Inventory Planning
Business Background
A hypothetical furniture manufacturer maintains raw materials, work-in-progress and finished goods.
The Challenge
Management lacks reliable information about closing inventory and frequently purchases unnecessary materials.
The Solution
The company improves stock classification, records material movements and reviews closing stock reports monthly.
Illustrative Outcome
Initial Average Inventory Investment: ₹20,00,000.
Revised Investment: ₹16,00,000.
Reduction:
₹20,00,000 − ₹16,00,000 = ₹4,00,000.
Percentage Reduction:
₹4,00,000 ÷ ₹20,00,000 × 100 = 20%.
The example assumes inventory reductions do not materially disrupt production.
Business Lesson
Accurate stock information can support better purchasing decisions and working capital management.
This case study is illustrative.
15. How Tally Prime Helps Calculate Closing Inventory
Tally Prime provides inventory management and valuation capabilities.
Businesses can maintain stock items, record purchases and sales, and review closing stock quantities and values.
Important capabilities include:
Stock Summary: Displays recorded inventory quantities and values.
Stock Item Masters: Maintain product details and relevant costing settings.
Inventory Vouchers: Record stock movements.
Godown Management: Track inventory across locations.
Stock Valuation Methods: Support different inventory costing approaches.
Physical Stock Vouchers: Help record verified quantities.
Stock Ageing Analysis: Supports review of older inventory.
Reorder Status: Helps identify replenishment requirements.
These features can improve stock visibility when transactions are recorded accurately.
16. How to View Closing Stock in Tally Prime
Businesses can review closing inventory through Stock Summary.
Step 1: Open the relevant company in Tally Prime.
Step 2: Press Alt+G (Go To).
Step 3: Search for Stock Summary.
Step 4: Select the required reporting period.
Step 5: Review stock groups and individual items.
Step 6: Examine closing quantities and values.
Step 7: Drill down into relevant transactions when necessary.
The displayed values depend on recorded transactions and configured costing methods.
Businesses should investigate unusual balances before relying on the figures for financial reporting.
17. How to Configure Inventory Valuation in Tally Prime
Tally Prime allows businesses to select costing methods for stock items.
To review the configuration:
Step 1: Open the relevant stock item master.
Step 2: Select the item for alteration.
Step 3: Review the applicable costing method.
Step 4: Select an appropriate method consistent with the company's accounting policy.
Step 5: Save the changes after suitable review.
Businesses can also compare inventory values using available valuation reporting options.
Changing a costing method can affect reported inventory values.
Such changes should therefore be evaluated carefully and discussed with the accountant where necessary.
18. Closing Inventory and Physical Stock Verification
Inventory software reflects recorded transactions.
However, actual quantities may differ because of damage, loss, incorrect entries or unrecorded movements.
Physical verification helps identify these differences.
Businesses should count inventory periodically and compare actual quantities with system balances.
Tally Prime provides Physical Stock vouchers for recording verified quantities.
Significant discrepancies should be investigated before adjustments are approved.
Physical verification is particularly important at financial year-end.
It helps improve confidence in closing stock quantities and related valuation.
19. Closing Inventory and Working Capital Management
Inventory represents money invested in goods and materials.
Excessive closing inventory may indicate unnecessary purchasing.
However, high closing stock is not always undesirable.
Seasonal demand, production requirements and supplier lead times may justify additional inventory.
Businesses should compare closing inventory with sales patterns, expected demand and purchasing requirements.
For example, a retailer preparing for a festive season may intentionally maintain higher stock.
Management should focus on inventory efficiency rather than simply reducing closing stock.
The objective is to maintain sufficient goods without unnecessarily blocking capital.
20. Common Closing Inventory Calculation Mistakes
Businesses should avoid several common errors.
One mistake is subtracting sales revenue instead of cost of goods sold.
Another is ignoring purchase returns or directly attributable acquisition costs.
Some businesses fail to record damaged or obsolete inventory.
Others use inconsistent valuation methods.
Incorrect opening balances can also affect subsequent calculations.
Stock transfers between warehouses should not be treated as sales.
Businesses must also ensure that inventory quantities and values relate to the correct reporting period.
Accurate closing inventory requires proper records, suitable valuation policies and physical verification.
21. Best Practices for Accurate Closing Inventory
Businesses should maintain consistent stock item names and units.
Purchases, sales, returns and adjustments should be recorded promptly.
Physical stock counts should be conducted regularly.
Damaged and obsolete inventory should be identified separately.
Inventory valuation policies should remain consistent and comply with applicable accounting requirements.
Management should review unusual changes in closing stock.
Tally Prime reports can support these reviews.
However, employees must understand the importance of accurate transaction recording.
Reliable closing inventory begins with disciplined daily inventory management.
Conclusion
Closing inventory is a fundamental component of accounting and business management.
The closing inventory formula helps businesses understand the value of goods remaining at the end of an accounting period.
Accurate calculations support cost of goods sold, gross profit, financial reporting and purchasing decisions.
Different inventory valuation methods may produce different results.
Businesses should therefore apply appropriate accounting policies and verify physical stock regularly.
Tally Prime supports closing inventory management through stock records, inventory vouchers, valuation methods and reporting capabilities.
For retailers, accurate closing stock helps identify unnecessary inventory investment.
For manufacturers, it supports material and finished goods planning.
For wholesalers, it improves stock visibility and financial decision-making.
Closing inventory is not simply the value of products left in a warehouse. It is an important measure of business resources, financial accuracy and future planning.
Powered by Binarysoft Technologies
Authorized Tally Partner
Binarysoft Technologies helps businesses implement and use Tally Prime for accounting, inventory management, closing stock valuation, warehouse tracking, purchasing and financial reporting.
Businesses seeking to improve inventory accuracy and financial reporting can benefit from appropriate Tally Prime configuration and structured stock management procedures.
Location:
1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact Us:
+91 7428779101, 9205471661
Email:
tally@binarysoft.com
Business Hours:
10:00 AM – 6:00 PM, Monday to Friday
Frequently Asked Questions
Which inventory valuation methods are commonly used?
FIFO, weighted average cost and specific identification are commonly used where appropriate under the applicable accounting framework.
Can Tally Prime calculate closing stock?
Yes. Tally Prime calculates recorded closing stock quantities and values using inventory transactions and configured valuation methods.
Why is physical stock verification important?
It helps identify differences between recorded inventory and actual stock, supporting more accurate financial reporting.
How does closing inventory affect gross profit?
Higher closing inventory reduces calculated cost of goods sold, assuming other figures remain unchanged, and therefore increases reported gross profit.
CA. Nivaan Agrawal works with MSMEs on bookkeeping, GST reporting, receivable management, and accounting automation. His professional focus is on making financial information easier for business owners to understand and manage.