Call CA Tally HelpDesk
+91 9205471661,
7428779101
Introduction: Why Budgetary Control Matters More Than Ever for Businesses in 2026
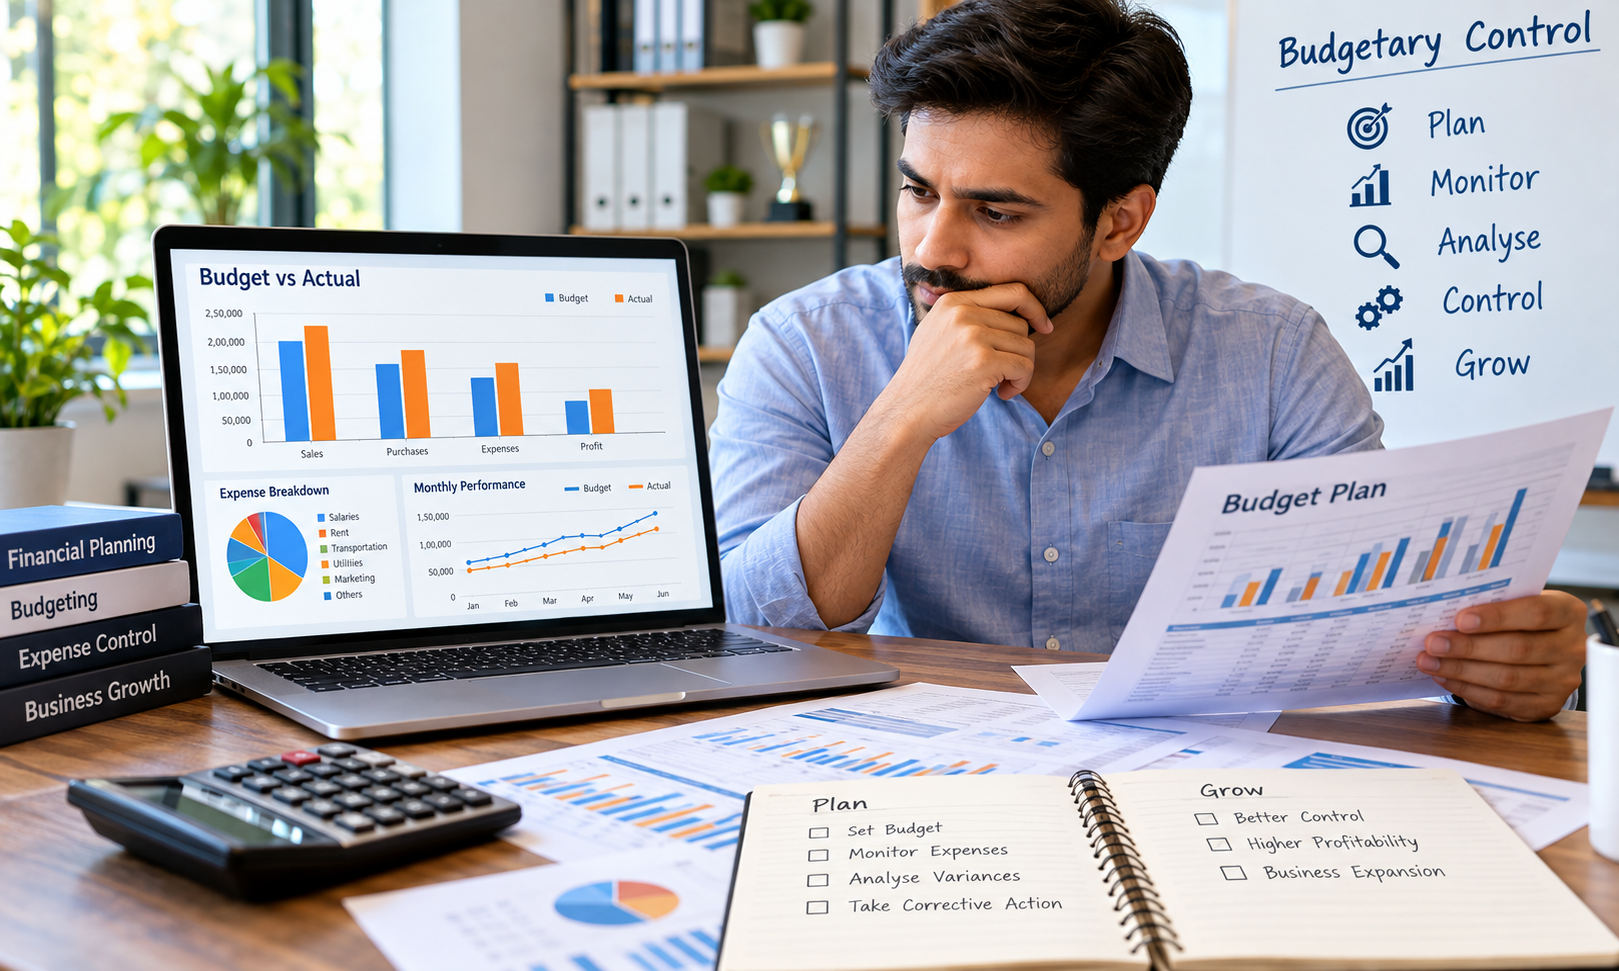
In 2026, business owners across India are managing rising operating costs, changing customer demand, competitive pricing and growing pressure to protect profit margins. For retailers, wholesalers, manufacturers and service providers, generating sales is no longer enough to ensure financial stability. Unplanned expenses, excessive inventory purchases, delayed collections and uncontrolled departmental spending can gradually weaken profitability. This is where budgetary control becomes an essential financial management practice. By establishing realistic budgets, comparing actual performance against planned targets and investigating significant differences, businesses can identify financial problems before they become serious. A structured budgetary control system helps management allocate resources efficiently, reduce unnecessary expenses and make informed decisions. With accounting software such as TallyPrime, businesses can create budgets, compare budgeted and actual figures and monitor financial performance through accounting reports. Understanding budgetary control can help organizations move from reactive financial management toward more disciplined, sustainable business growth.
A Business Owner's Story: When Rising Sales Could Not Protect Profit
Amit operated a growing electrical goods distribution business in Delhi. His warehouse was busy, customer orders were increasing and employees were regularly handling new deliveries.
From the outside, the business appeared successful.
However, at the end of the financial year, Amit discovered something unexpected.
Despite higher sales, his net profit had declined.
Warehouse rent had increased, transportation expenses were rising and additional purchases had created excess inventory.
Amit had approved expenses whenever they seemed necessary, but he had never established a clear monthly spending budget.
One evening, while reviewing his accounts, he asked his accountant a difficult question:
"How can we be selling more every month but keeping less money?"
His accountant explained that revenue growth and financial discipline were two different things.
The business needed a structured budget and a process for comparing planned expenses with actual spending.
Amit began preparing departmental budgets and reviewing budget variances every month using TallyPrime.
Gradually, he gained better visibility into transportation costs, inventory purchases, employee expenses and administrative spending.
Instead of discovering problems at year-end, he could investigate unusual expenses during the month.
The experience changed his approach to financial management.
He realized that successful business management is not only about earning more revenue, but also about understanding where every rupee is being spent.
This is an illustrative story created to explain the importance of budgetary control.
1. What Is Budgetary Control?
Budgetary control is a financial management process in which an organization prepares budgets for a defined period, compares actual financial results against those budgets and takes corrective action when significant differences arise.
A budget represents a financial plan, while budgetary control is the ongoing process of monitoring and managing performance against that plan.
For example, a trading business may establish a monthly transportation budget of ₹80,000.
If actual transportation expenses reach ₹1,05,000, management can investigate the ₹25,000 overspending.
The objective is not simply to restrict expenses. It is to ensure that financial resources are used effectively to achieve business goals.
Budgetary control helps businesses evaluate financial performance, assign responsibility and improve future planning.
2. Main Objectives of Budgetary Control
Financial Planning
Budgetary control encourages businesses to estimate expected income, expenses and resource requirements before beginning an accounting period.
This allows management to prepare for future financial commitments.
Expense Management
By establishing spending limits and monitoring actual expenditure, businesses can identify unnecessary costs and reduce waste.
Better Resource Allocation
Management can distribute financial resources among departments according to operational requirements and business priorities.
Profitability Improvement
Budgetary control helps organizations monitor expenses, identify inefficiencies and protect profit margins.
Performance Evaluation
Actual results can be compared with financial targets to assess departmental and organizational performance.
Management Coordination
Budgets encourage departments such as sales, purchases, production and administration to work toward common financial objectives.
Accountability
Budget responsibility can be assigned to specific managers or departments, helping organizations understand the reasons for financial deviations.
3. Important Features of Budgetary Control
An effective budgetary control system generally includes clearly defined financial objectives, realistic budgets, assigned responsibilities, periodic performance reviews and corrective action.
Budgets should be prepared for specific periods such as months, quarters or financial years.
Management must ensure that accounting information is accurate and available on time.
A useful budgetary control system should also allow flexibility when business conditions change significantly.
For example, an unexpected increase in raw material prices may require a revised purchasing budget.
Budgetary control works best when it supports practical decision-making rather than becoming an inflexible spending restriction.
4. Types of Budgets Used in Budgetary Control
Different budgets serve different financial and operational purposes.
|
Type of budget
|
Purpose
|
|---|
|
Sales Budget
|
Estimates expected sales revenue
|
|
Purchase Budget
|
Plans inventory and material purchases
|
|
Production Budget
|
Estimates production quantities and resources
|
|
Cash Budget
|
Forecasts expected cash receipts and payments
|
|
Expense Budget
|
Establishes limits for operating expenses
|
|
Capital Expenditure Budget
|
Plans investment in machinery, equipment and infrastructure
|
|
Master Budget
|
Combines major functional budgets into an overall financial plan
|
|
Flexible Budget
|
Adjusts budgeted amounts according to activity levels
|
Sales Budget
A sales budget estimates expected revenue based on sales forecasts, historical trends, customer demand and market conditions.
For example, a wholesaler may plan quarterly sales of ₹75 lakh.
The sales team can monitor actual revenue against the target and investigate significant differences.
Purchase Budget
A purchase budget helps businesses plan inventory procurement and avoid excessive stock accumulation.
It is particularly useful for retailers, wholesalers and distributors.
Cash Budget
A cash budget forecasts expected receipts and payments.
It helps businesses identify potential cash shortages and plan supplier payments, employee salaries and other obligations.
Expense Budget
Expense budgets establish expected spending for rent, transportation, electricity, salaries, marketing and administration.
Capital Expenditure Budget
This budget supports decisions involving long-term investments such as machinery, vehicles, computers and warehouse infrastructure.
5. Budgetary Control Process: Step-by-Step Explanation
Budgetary control is a continuous process involving planning, monitoring, analysis and corrective action.
Budgetary Control Cycle
Prepare realistic budgets
Assign departmental responsibility
Record actual transactions
Investigate variances and take action
Repeat the cycle for the next reporting period, using lessons from actual performance.
Step 1: Establish Financial Objectives
Management must define measurable goals such as increasing sales, improving gross profit margins, reducing administrative expenses or improving cash flow.
Step 2: Prepare Budgets
Historical financial data, market conditions, expected demand and operational requirements should be considered while preparing budgets.
Step 3: Assign Responsibilities
Department managers should understand their budgets and the financial targets they are expected to achieve.
Step 4: Record Actual Transactions
Accurate accounting records are essential for meaningful budget comparisons.
Sales, purchases, payments and expenses should be recorded promptly.
Step 5: Compare Budgeted and Actual Performance
Management should periodically compare actual financial results with approved budgets.
Step 6: Investigate Significant Variances
Differences should be analysed to determine whether they arise from higher prices, increased activity, inefficiency or changing market conditions.
Step 7: Implement Corrective Measures
Corrective actions may include renegotiating supplier rates, reducing unnecessary expenses, revising inventory purchasing or updating financial forecasts.
6. Budgetary Control Example with Practical Calculations
Consider a wholesale trading business that has established the following monthly expense budget.
|
Expense category
|
Budget
|
Actual
|
Variance
|
|---|
|
Employee Salaries
|
₹2,00,000
|
₹2,10,000
|
₹10,000 U
|
|
Warehouse Rent
|
₹80,000
|
₹80,000
|
₹0
|
|
Transportation
|
₹70,000
|
₹95,000
|
₹25,000 U
|
|
Electricity
|
₹25,000
|
₹22,000
|
₹3,000 F
|
|
Marketing
|
₹50,000
|
₹40,000
|
₹10,000 F
|
|
Total
|
₹4,25,000
|
₹4,47,000
|
₹22,000 U
|
U = Unfavourable variance; F = Favourable variance, based on expense control.
Budget Variance Formula
\[ \text{Expense Variance}=\text{Actual Expense}-\text{Budgeted Expense} \]
For transportation:
\[ ₹95,000-₹70,000=₹25,000 \]
The business exceeded its transportation budget by ₹25,000, or approximately 35.7%.
This variance should be investigated.
Possible reasons include increased delivery frequency, higher fuel costs, inefficient route planning or unexpected transportation requirements.
However, a favourable variance does not always mean better performance. Lower marketing expenditure, for example, may also result from cancelled campaigns that could affect future sales.
7. How TallyPrime Helps Businesses Implement Budgetary Control
TallyPrime provides budgeting and accounting capabilities that help businesses establish financial targets and compare them with recorded transactions.
Creating Budgets
Businesses can define budgets for accounting groups, ledgers and cost centres, subject to the applicable configuration.
Budgets can cover specific periods, such as a month, quarter or financial year.
For example, management may create an annual administrative expense budget and monitor spending against it.
Budget vs Actual Reporting
TallyPrime supports budget variance reporting, allowing businesses to compare planned financial figures with actual results.
This helps identify departments or expense categories requiring attention.
Cost Centre Management
Cost centres allow businesses to allocate relevant income and expenses to departments, branches or business activities.
A company may create separate cost centres for sales, administration, warehouse operations and marketing.
Combined with appropriate budgeting, this helps evaluate departmental performance.
Expense Monitoring
Businesses can maintain expense ledgers for transportation, salaries, rent, electricity, repairs and other operating costs.
Accurate ledger classification improves the usefulness of budget comparisons.
Sales and Purchase Analysis
TallyPrime's sales and purchase reports provide financial information that management can use to assess performance against operational targets.
Financial Statements
Profit and Loss Statements, Balance Sheets and other reports help management evaluate overall financial performance.
Budget reports should be reviewed alongside these statements for a more complete understanding.
8. Step-by-Step: Creating a Budget in TallyPrime
The following is a general workflow. Exact navigation may vary depending on the TallyPrime release and enabled features.
Step 1: Open the Company
Launch TallyPrime and select the company for which the budget will be created.
Step 2: Enable Budget Features
Open the company features through F11 and enable the applicable budgeting options.
Enable cost centre features if departmental budgeting is required.
Step 3: Create a Budget
Navigate to the budget creation screen through the available masters or budget management options.
Enter a suitable name, such as Annual Operating Budget.
Step 4: Define the Budget Period
Specify the starting and ending dates.
For example, an annual budget may cover 1 April to 31 March.
Step 5: Allocate Budget Amounts
Select the relevant accounting groups, ledgers or cost centres.
Enter the budgeted values for income or expenses as appropriate.
Step 6: Record Business Transactions
Record sales, purchases, payments, receipts and journal entries using the appropriate vouchers.
Step 7: Review Budget Variance Reports
Open the applicable budget variance report and compare actual figures against budgeted amounts.
Investigate material deviations and decide whether corrective action or an approved budget revision is required.
9. Case Study 1: Retail Chain Reduces Uncontrolled Operating Expenses
Illustrative case study: A multi-location retail business strengthens expense control through departmental budgeting.
A retail business operating three stores in Delhi experienced increasing operational expenses despite consistent customer demand.
Store managers independently approved transportation, maintenance and promotional expenditure.
The business lacked a consolidated budget monitoring process.
The Challenge
Monthly operating costs had increased significantly, and management could not easily identify which locations were responsible for the higher expenditure.
The Solution
The company introduced departmental budgets and began recording branch-related expenses using appropriate cost centre allocations in TallyPrime.
Management reviewed budget variances every month and investigated unusual spending.
Illustrative Results
|
Performance indicator
|
Before
|
After
|
|---|
|
Monthly operating expenses
|
₹6.5 lakh
|
₹5.8 lakh
|
|
Budget review frequency
|
Quarterly
|
Monthly
|
|
Expense reporting
|
Consolidated only
|
Branch-wise
|
In this hypothetical example, operating expenses declined by approximately 10.8%.
The company also gained better visibility into spending across its stores.
Key takeaway: Budgetary control helped management identify avoidable costs and assign financial responsibility to individual locations.
10. Case Study 2: Manufacturing Business Improves Material Cost Planning
Illustrative case study: A small manufacturer improves purchasing discipline through budget planning.
A manufacturing company in Faridabad produced metal components for industrial customers.
Raw material prices fluctuated frequently, making production cost planning difficult.
The Challenge
The purchasing department placed orders based primarily on immediate production requirements.
Management often discovered higher material costs only after reviewing monthly financial statements.
The Solution
The company introduced monthly purchasing budgets based on expected production volumes and material requirements.
TallyPrime was used to maintain purchase records, inventory information and financial reports.
Budget variance reviews were combined with purchasing and stock analysis.
Illustrative Results
|
Performance indicator
|
Before
|
After
|
|---|
|
Monthly material expenditure
|
₹12 lakh
|
₹11.2 lakh
|
|
Purchase budget review
|
Irregular
|
Monthly
|
|
Material purchasing process
|
Reactive
|
Planned
|
In this hypothetical scenario, monthly material expenditure decreased by approximately 6.7%.
The company improved purchasing coordination and gained better control over inventory-related spending.
Key takeaway: Budgetary control supported better procurement planning, while accounting and inventory reports provided the information needed to evaluate actual results.
11. Key Benefits of Budgetary Control for Growing Businesses
Better Financial Discipline
Budgetary control encourages managers to evaluate expenses before approving them.
This reduces the risk of unnecessary spending and improves accountability.
Improved Profitability
Monitoring actual costs against planned expenditure can help businesses identify inefficiencies and protect profit margins.
Stronger Cash Flow Planning
Cash budgets help organizations anticipate upcoming financial commitments and prepare for periods of lower collections.
Better Inventory Management
Purchase and inventory budgets help businesses avoid excessive procurement and reduce unnecessary working capital investment.
Improved Decision-Making
Budget variance reports provide management with information about areas requiring corrective action.
Greater Departmental Accountability
Assigning budget responsibility to departments encourages more disciplined use of organizational resources.
Early Identification of Financial Problems
Regular comparisons help businesses identify rising expenses or falling revenue before problems become more difficult to manage.
12. Limitations of Budgetary Control
Although budgetary control offers significant advantages, businesses should understand its limitations.
Budgets depend on assumptions about future sales, expenses and operating conditions. Unexpected market changes can make original estimates unrealistic.
Preparing detailed budgets may require considerable time, especially for organizations with multiple departments.
Excessively rigid spending limits can also discourage useful investments or operational improvements.
Another limitation is that financial performance cannot always be evaluated using spending figures alone.
For example, higher transportation expenditure may be justified if sales volumes increase substantially.
Businesses should therefore combine budgetary control with operational performance analysis.
13. Budgetary Control vs Budgeting: Understanding the Difference
Budgeting and budgetary control are closely related but serve different purposes.
|
Budgeting
|
Budgetary control
|
|---|
|
Involves preparing financial plans
|
Involves monitoring performance against plans
|
|
Focuses on expected future results
|
Focuses on actual results and corrective action
|
|
Establishes financial targets
|
Evaluates whether targets are achieved
|
|
Primarily a planning activity
|
A continuous management process
|
|
Produces approved budgets
|
Produces variance analysis and management decisions
|
Budgeting is the starting point, while budgetary control ensures that financial plans are actively monitored and managed.
14. Best Practices for Effective Budgetary Control
Businesses should establish realistic financial targets based on historical performance, expected demand and current operating conditions.
Budgets should be prepared with input from the departments responsible for implementing them.
Management should review important expense categories regularly and investigate significant variances.
Where activity levels fluctuate, flexible budgets can provide more meaningful comparisons than fixed budgets.
Businesses should also distinguish between controllable expenses and costs affected by external factors.
TallyPrime can support these practices through systematic accounting records, budget comparisons, cost centre allocations and financial reporting.
However, management must still interpret the reports and decide which corrective actions are appropriate.
15. How Budgetary Control Supports Long-Term Business Growth
Budgetary control is not merely a cost-cutting technique.
It is a management approach that connects financial planning with business strategy.
A company planning to open a new branch, expand warehouse capacity or introduce a product line needs reliable financial estimates.
Budgeting helps management assess the resources required, while budgetary control helps monitor how those resources are actually used.
When combined with accurate accounting records, regular financial reviews and informed decision-making, budgetary control can support sustainable expansion.
For businesses using TallyPrime, disciplined accounting and budget monitoring can create a stronger foundation for financial management.
Conclusion
Budgetary control is an essential financial management practice that helps businesses plan expenditure, monitor performance and improve resource utilization.
By preparing realistic budgets, comparing actual results with planned targets and investigating significant variances, organizations can identify financial risks and make better management decisions.
Retailers, wholesalers, manufacturers, distributors and service providers can all benefit from structured budgetary control.
TallyPrime supports this process through budgeting features, cost centre accounting, financial reports and budget variance analysis.
However, successful budgetary control requires more than software. It depends on accurate accounting, management involvement, realistic planning and timely corrective action.
Businesses that consistently review their budgets can improve financial discipline, protect profitability and build a stronger foundation for long-term growth.
Powered by Binarysoft Technologies
Authorized Tally Partner
Location: 1626/33, 1st Floor, Naiwalan, Karol Bagh, New Delhi – 110005, INDIA
Contact us: +91 7428779101, 9205471661
Email us: tally@binarysoft.com
Business Hours: 10:00 AM – 6:00 PM, Monday to Friday
Website: tallyatcloud.com
Frequently Asked Questions
Can TallyPrime be used for budgetary control?
Yes. TallyPrime supports budgeting and budget variance reporting, allowing businesses to compare planned financial figures with actual accounting results.
What is the difference between budgeting and budgetary control?
Budgeting involves preparing financial plans, while budgetary control involves monitoring actual performance against those plans and implementing corrective measures.
Which businesses benefit most from budgetary control?
Retailers, wholesalers, manufacturers, distributors, service providers and other organizations with recurring operating expenses can benefit from structured budgetary control.
Can budgetary control improve profitability?
Yes. Budgetary control can improve profitability by helping businesses identify unnecessary expenses, operational inefficiencies and opportunities for better resource utilization.
Can budgetary control help prevent cash shortages?
Budgetary control, particularly cash budgeting, can help businesses anticipate future receipts and payments and identify potential cash shortages before they occur.
CA. Reyansh Kulkarni has expertise in GST advisory, accounting compliance, and financial planning. He frequently contributes articles on digital accounting, inventory management, and modern financial practices for businesses.